L’argent, le moteur des marchés
Have global PMI new orders peaked?
13 novembre 2026 par Simon Ward
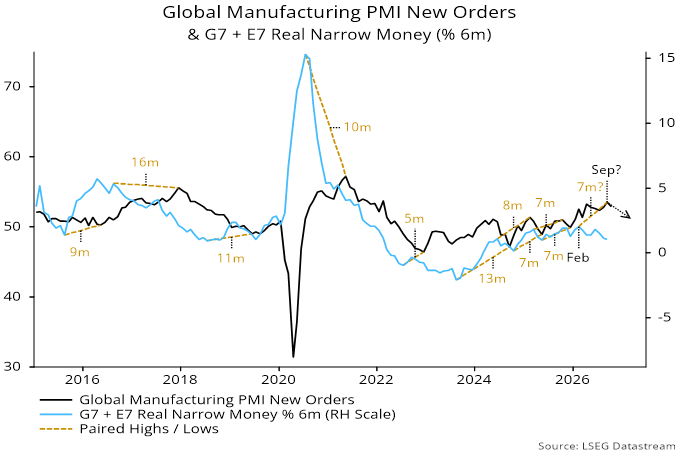
Previous posts suggested that a fall in global six-month real narrow money momentum since February would be reflected in a decline in manufacturing PMI new orders from around September, based on a recent seven-month lead at turning points. Orders cooled on schedule in October – see chart 1.
Chart 1
Two other developments support the conjecture that September marked a significant PMI peak. First, monthly momentum of the OECD’s G7 leading index slowed for a third month in October. The index has displayed a short lead on PMI new orders historically, although initial results are often revised – chart 2.
Chart 2
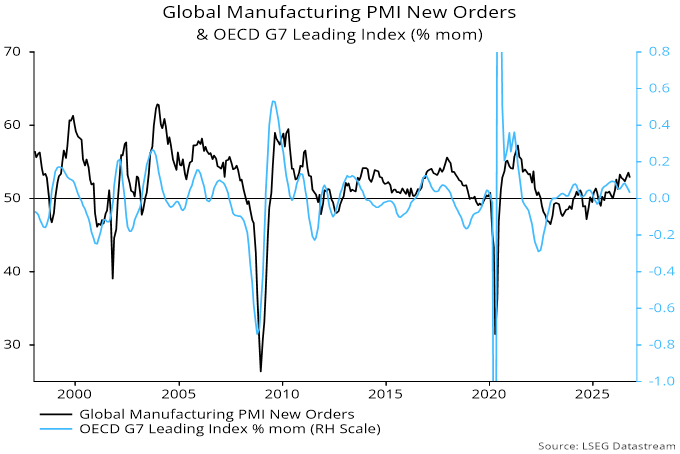
Note that the leading indices for six of the G7 countries exclude any measure of money (Canada is the exception), so the recent slowdown represents independent corroboration of the monetary signal.
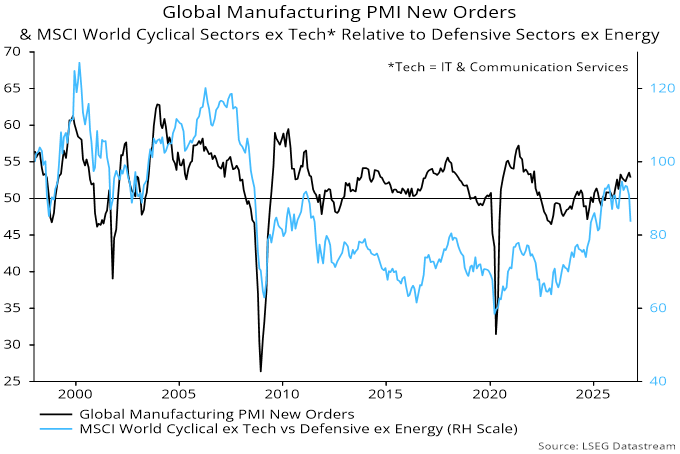
Secondly, the October PMI pull-back has been accompanied by sharp underperformance of equity market cyclical sectors versus defensive sectors. Similar-sized moves in the cyclical relative historically were associated with sustained / significant PMI declines – chart 3.
Chart 3