The long-standing view here has been that the 3- to 5-year stockbuilding cycle would enter a downswing in 2026, reaching a low by end-2027.

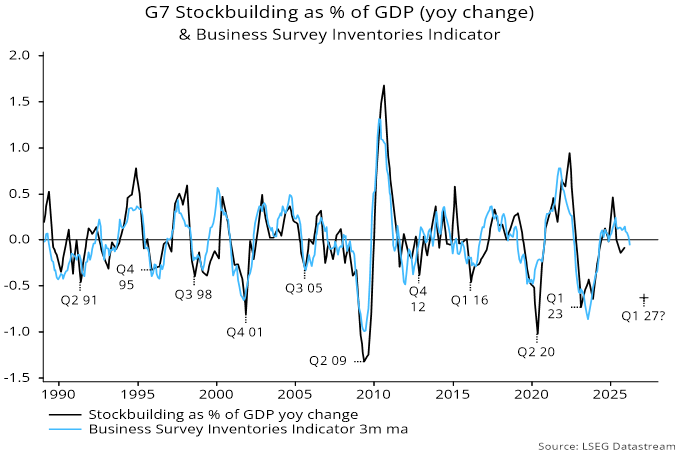
The key measure used to track the cycle is the annual change in G7 stockbuilding, expressed as a percentage of GDP. This is supplemented by a more timely indicator derived from business surveys, which displays a strong correlation with the GDP measure – see chart 1.

Chart 1
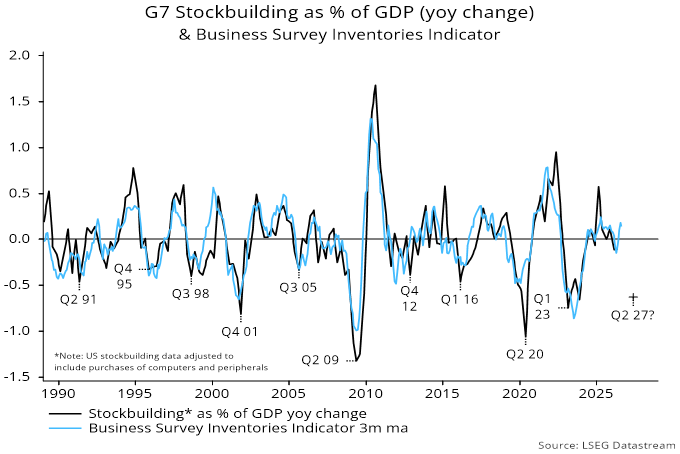
Chart 1 showing G7 Stockbuilding as % of GDP (yoy change) & Business Survey Inventories Indicator

The GDP indicator last bottomed in Q1 2023, implying that the current upswing is mature, already matching the historical average duration of a whole cycle (of 3.5 years).

The GDP measure reached a level consistent with a peak in Q1 2025 but stockbuilding behaviour around that time was distorted by front-running of US tariffs. A correction over subsequent quarters has run its course, with the business survey indicator signalling a strong rebound in Q3 2026. This is supported by other evidence, e.g. the Atlanta Fed US GDP nowcast currently estimates that stockbuilding will contribute 2.0 pp to annualised Q3 growth.

The judgement here, therefore, is that the cycle is reaching a final peak in Q3 ahead of a multi-quarter downswing.

The cycle describes demand for production inputs – both raw materials and semi-manufactures, including electronic components – so is strongly correlated with their prices. A further rise in year-on-year growth of industrial commodity prices and global semiconductor sales in Q3 is consistent with the cycle reaching a peak – chart 2.

Chart 2
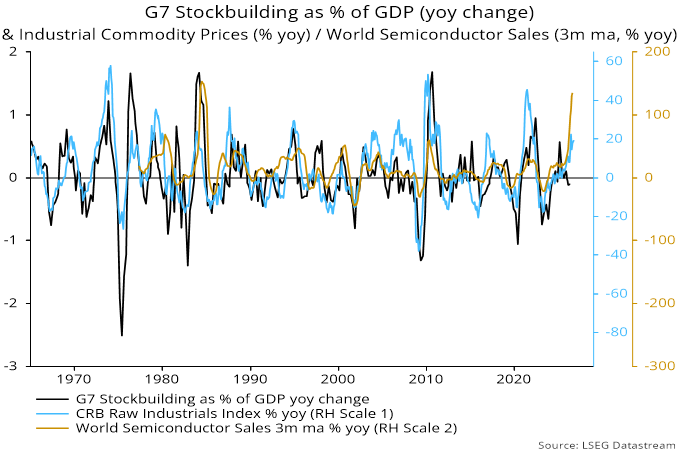
Chart 2 showing G7 Stockbuilding as % of GDP (yoy change) & Industrial Commodity Prices (% yoy) / World Semiconductor Sales (3m ma, % yoy)

The suggestion is that the cycle about to shift from providing a tailwind to global economic momentum and pricing power to acting as a progressive headwind, with a maximum negative impact in mid-to-late 2027.

The risk of economic weakness next year is magnified by signs that a downswing in the long-term housing cycle is on track to accelerate into a 2027-28 low. The cycle has averaged 18 years historically, with the last trough reached in 2009.

The behaviour of homebuilding stocks may provide a clue to the timing of the next low. Chart 3 shows that an average of stock prices of US and UK homebuilders reached a peak 47 and 37 months respectively before lows in the last two housing cycles, in 1991 and 2009, while UK prices peaked 33 months before a previous trough in 1975.

Chart 3
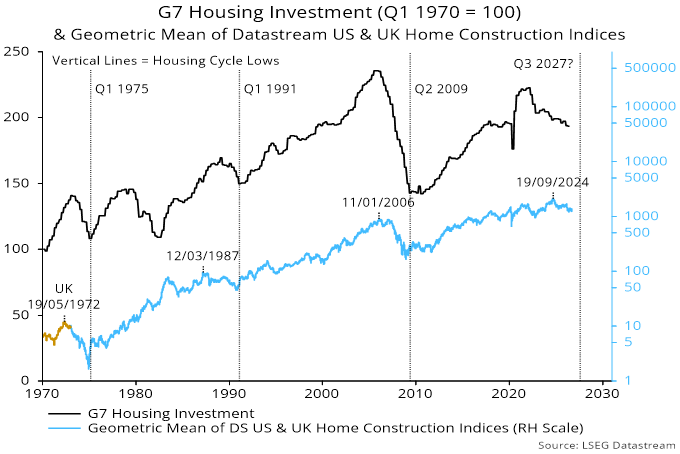
Chart 3 showing G7 Housing Investment (Q1 1970 = 100) & Geometric Mean of Datastream US & UK Home Construction Indices

The most recent peak in the average occurred in September 2024, suggesting a cycle trough between June 2027 and August 2028.

UK homebuilding stocks broke below a 2025 low in March and have yet to regain this level. US stocks currently remain above the corresponding low; an equivalent breakdown would suggest an acceleration of the cycle downswing – chart 4.

Chart 4
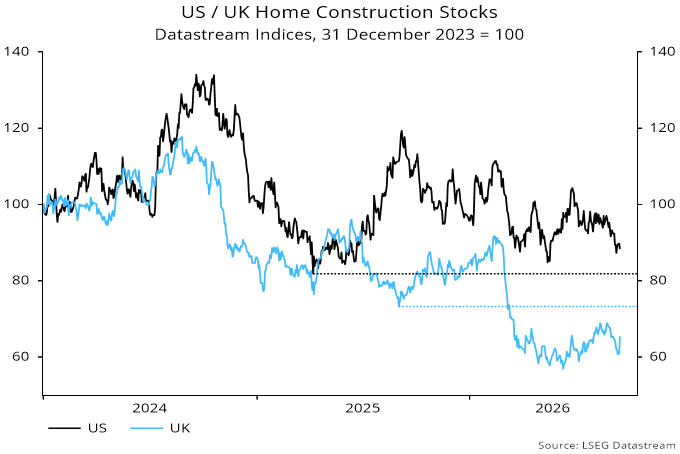
Chart 4 showing US / UK Home Construction Stocks Datastream Indices, 31 December 2023 = 100

Joint weakness of the stockbuilding and housing cycles in 2027 would likely overpower and / or shorten the current business investment cycle upswing.
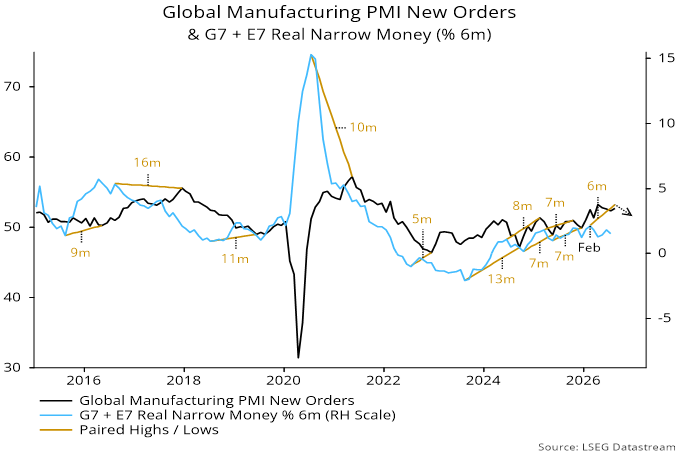
Money trends suggest that global economic momentum is peaking in Q3, with downside risk focused on Europe and Japan.

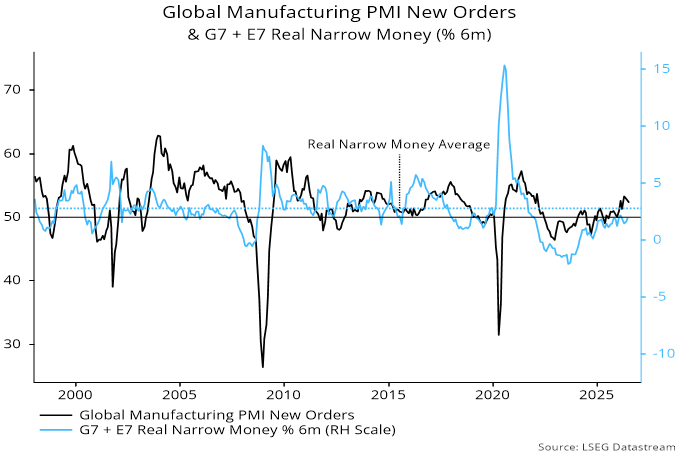
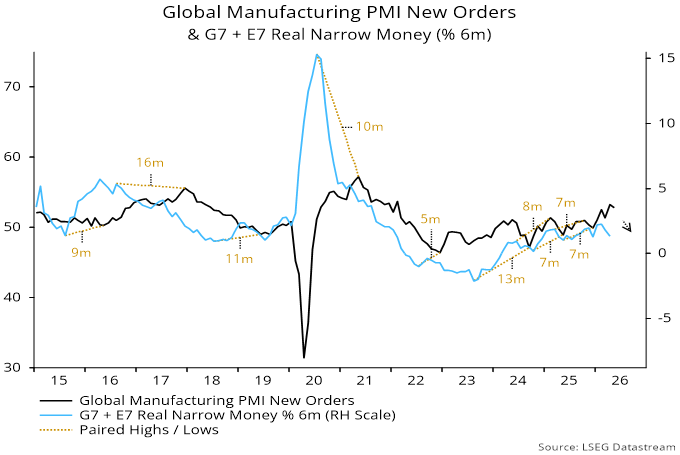
The global manufacturing PMI new orders index rose in August, though remains below an April high – see chart 1.

Chart 1

Chart 1 showing Global Manufacturing PMI New Orders & G7 + E7 Real Narrow Money (% 6m)

The solid August result is consistent with a rise in global six-month real narrow money momentum into early 2026. Growth, however, has eased since February, suggesting a moderation in new orders over the remainder of the year.

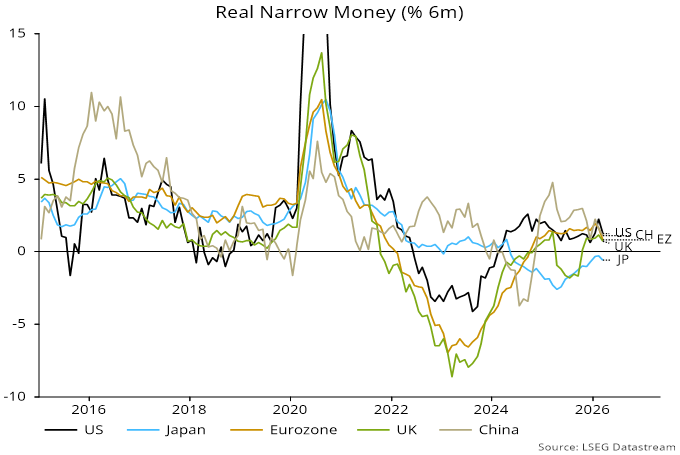
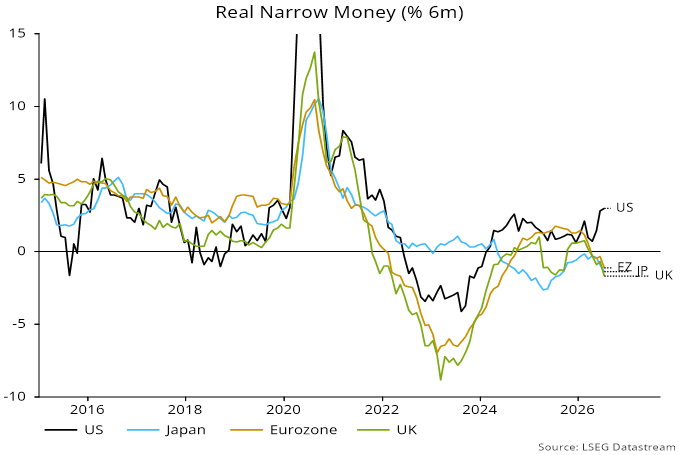
A July fall in real money momentum reflected deepening contractions in Europe and Japan, which offset a further pick-up in the US – chart 2.

Chart 2

Chart 2 showing Real Narrow Money (% 6m)

The suggestion is that the US economy is running hot with the Fed behind the curve, while ECB and BoJ policy tightening is misguided, risking a sharp economic slowdown, or worse.

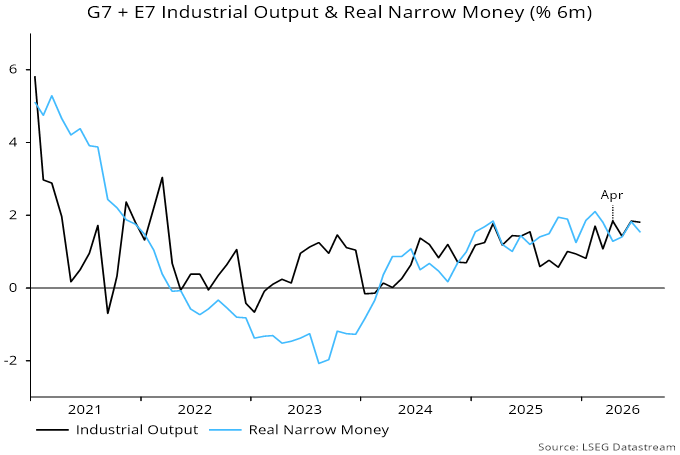
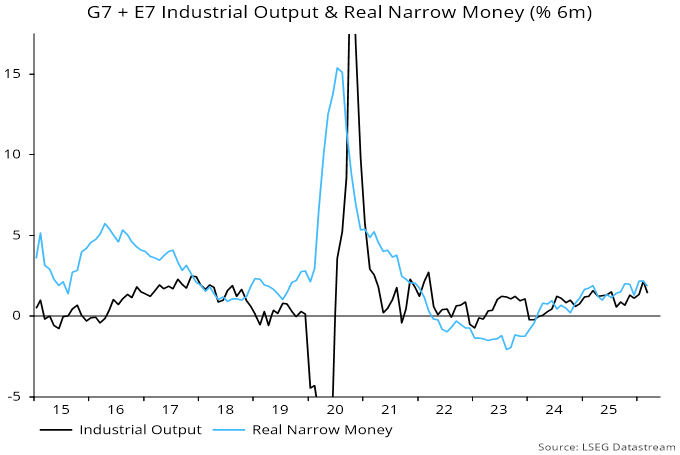
Meanwhile, six-month growth of global real narrow money is estimated to have fallen below that of industrial output in July, implying a less favourable liquidity backdrop for markets – chart 3.

Chart 3

Chart 3 showing G7 + E7 Industrial Output & Real Narrow Money (% 6m)

A previous undershoot in April preceded a sharp correction in momentum stocks but real money growth recovered to close the gap in May / June, following which equity indices reached new highs.

The global services PMI survey for August was stronger than for manufacturing, with new business reaching a 20-month high. Services buoyancy, however, has little implication for manufacturing prospects. Granger-causality tests show that manufacturing new orders predict services new business but not vice versa. Manufacturing deceleration is likely to be reflected in services cooling.

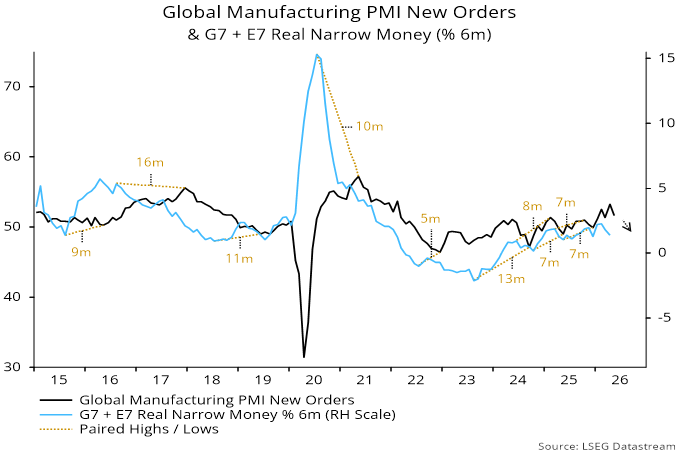
Global six-month real narrow money growth recovered further in June but remains below a February peak, as well as its long-term average – see chart 1.

Chart 1

Chart 1 showing Global Manufacturing PMI New Orders & G7 + E7 Real Narrow Money (% 6m)

The earlier slowdown suggested that the global industrial economy would lose some momentum during H2. A cooling may already have begun, with manufacturing PMI new orders easing for a third successive month in July. Still, the latest uptick in real money growth argues against significant weakness, at least through year-end.

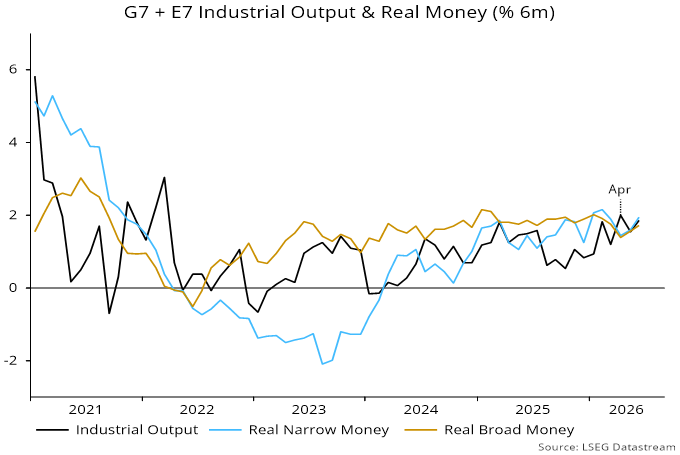
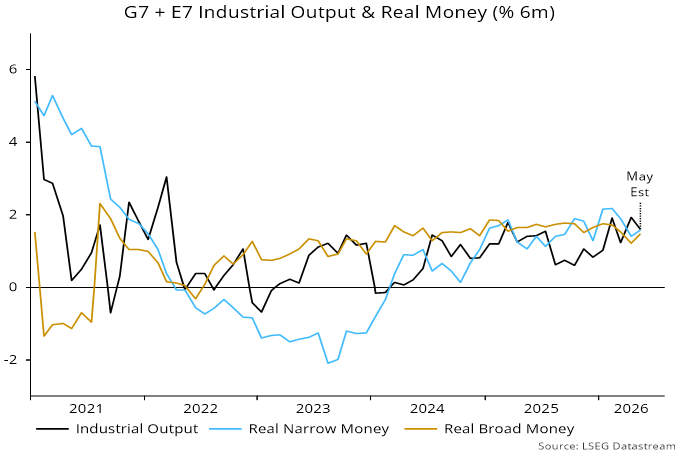
The recent violent correction in momentum stocks followed global six-month real money growth – on both narrow and broad definitions – crossing below industrial output expansion in April, suggesting a loss of “excess” money support for markets. Real narrow money growth reconverged with output expansion in May / June, with real broad money growth slightly weaker – chart 2. This suggests a neutral monetary backdrop for markets, in contrast to positive conditions in late 2025 / early 2026.

Chart 2

Chart 2 showing G7 + E7 Industrial Output & Real Money (% 6m)

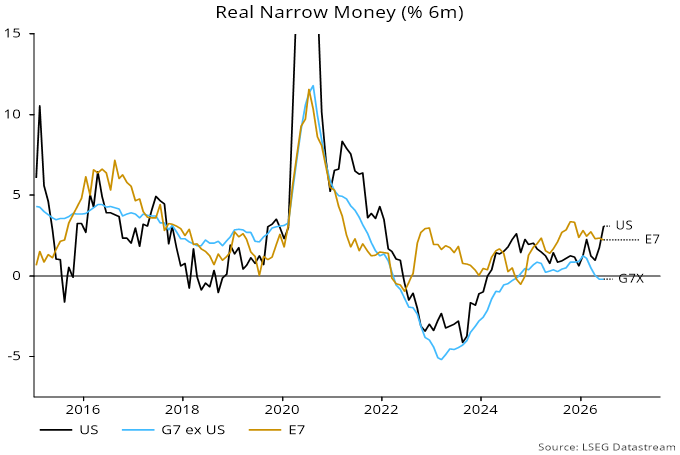
The rise in real money growth has been driven by US acceleration / strength, contrasting with weakness in the rest of the G7 – chart 3. Such divergence is unhealthy, suggesting a misalignment of policy stances, a correction of which could lead to further monetary / market volatility.

Chart 3

Chart 3 showing Real Narrow Money (% 6m)

Global six-month real money growth has fallen back since early 2026, crossing below industrial output expansion in April – see chart 1. This suggests that the global economy will lose some momentum during H2, while the monetary backdrop for markets has become less favourable, at least temporarily.

Chart 1

G7 + E7 Industrial Output & Real Money (% 6m)

From a cyclical perspective, housing indicators remain weak, while the stockbuilding cycle appears to be reaching a peak, with a downswing likely to extend well into 2027.

The optimistic case is that real money growth will be supported by a reversal of the H1 boost to inflation from higher energy prices, assuming that the reopening of the Persian Gulf proves lasting, while the business investment cycle remains in an upswing driven by seemingly insatiable demand for AI compute. Still, upward pressure on financing costs from the vast spending could start to constrain momentum soon, while the disinflation lift to real money growth could be offset by slower nominal expansion, reflecting H1 interest rate rises.

A conservative view of equity market prospects, therefore, appears warranted, as least until monetary indicators give an “all-clear” signal. The cyclical framework employed here suggests that equities will perform poorly over the medium term: weak phases in the three investment cycles are scheduled to coincide at some point in 2027-28,  a condition historically associated with major bear markets.

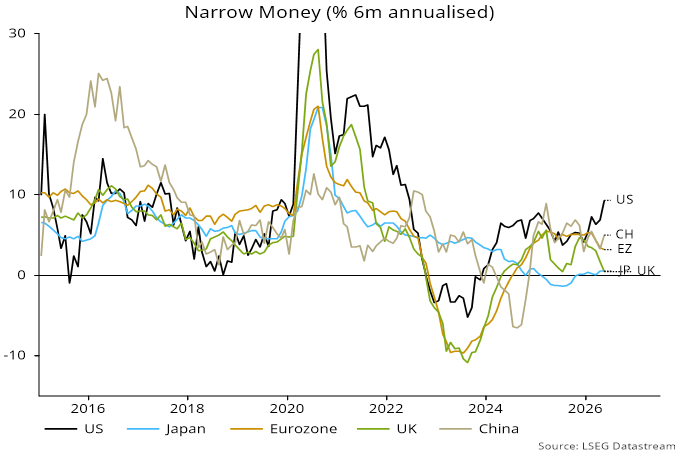
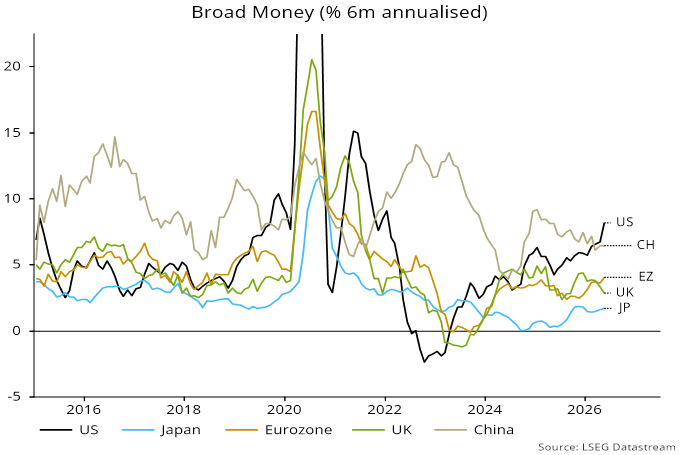
An important recent change has been a divergence of money growth across major economies, with US expansion picking up to a level inconsistent with 2% inflation, in contrast to weakness in Europe and Japan – see charts 2 and 3. This suggests superior US near-term economic prospects and a need for opposite monetary policy adjustments. If forthcoming, these could sustain a recent recovery in the US dollar, likely acting as another headwind for markets.

Chart 2

Narrow Money (% 6m annualised)

Chart 3

Broad Money (% 6m annualised)

US monetary acceleration gathered pace after the Fed’s December decision to resume balance sheet expansion, a policy that Chair Warsh wants to reverse. Action is unlikely before late 2026 but – if combined with a near-term interest rate rise – could cause money growth to slow sharply in H1 2027.

Despite US strength, global annual broad money growth is below its pre-pandemic (i.e. 2015-19) average, reflecting softness in China as well as Europe / Japan. This suggests that inflationary pressures globally will remain contained, even if US medium-term risks are rising.

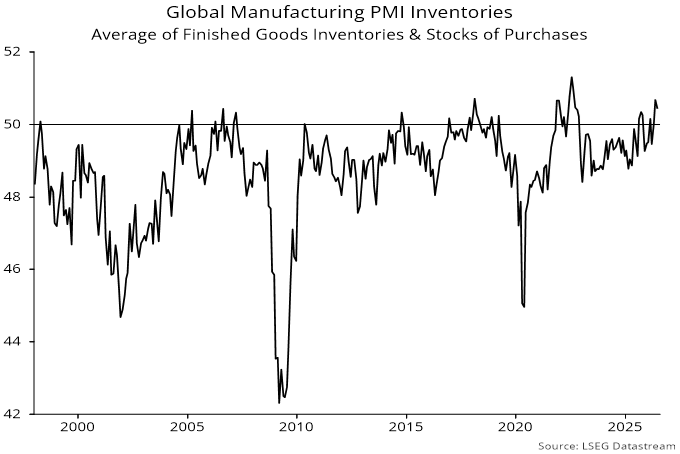
The judgement that the stockbuilding cycle is peaking is supported by the global manufacturing purchasing managers’ survey, with an average of the finished goods inventories and stocks of purchases indices reaching its fifth highest level on record in May – chart 4. Downswings in the cycle were historically associated with underperformance of cyclical sectors – notably materials, financials and communication services – versus defensive sectors, especially health care and consumer staples.

Chart 4

Global Manufacturing PMI Inventories Average of Finished goods Inventories & Stocks of Purchases

Cycle fluctuations were also reflected in prices of production inputs including electronic components as well as industrial commodities. A coming downswing could challenge optimistic forecasts for medium-term earnings growth of chipmakers and other hardware suppliers.

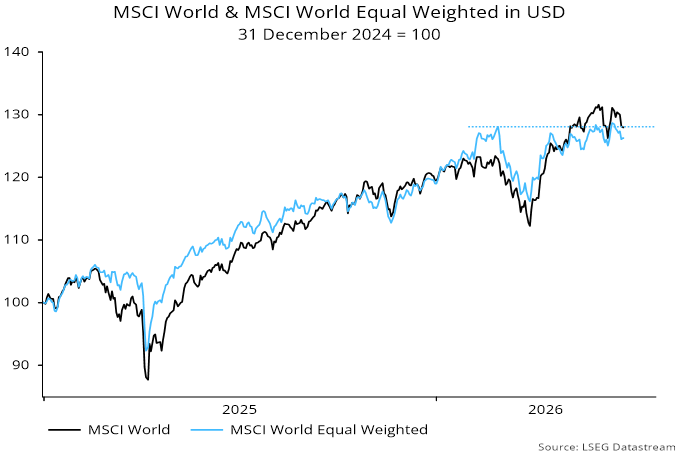
Global equities have lost momentum. The MSCI World index is little changed since mid-May. The equal-weight version of the index remains below a high reached in late February – see chart 1.

Chart 1

Chart 1 showing MSCI World & MSCI World Equal Weighted in USD 31 December 2024 = 100

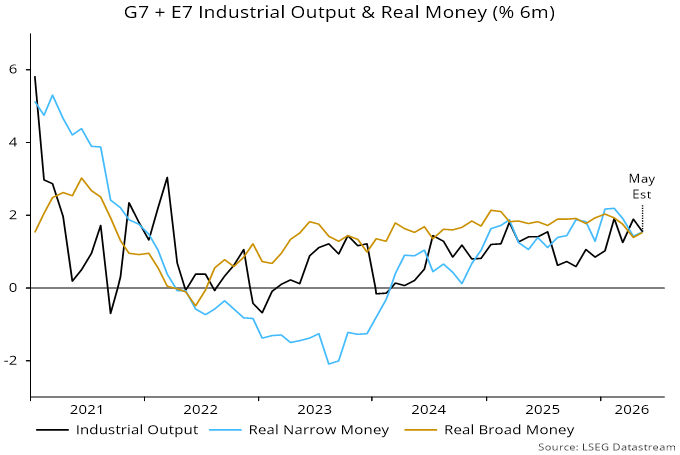
The stall could be explained by a less favourable “excess” money backdrop. Six-month growth of global (i.e. G7 plus E7) real money – on both narrow and broad definitions – crossed below that of industrial output in April. Narrow money growth was higher over August-March, while the broad money gap had been positive in most months since end-2022 – chart 2.

Chart 2

Chart 2 showing G7 + E7 Industrial Output & Real Money (% 6m)

Real money growth rates appear to have recovered in May but may not have moved back above output expansion, based on partial information.

Prospects for a restoration of excess money support are mixed.

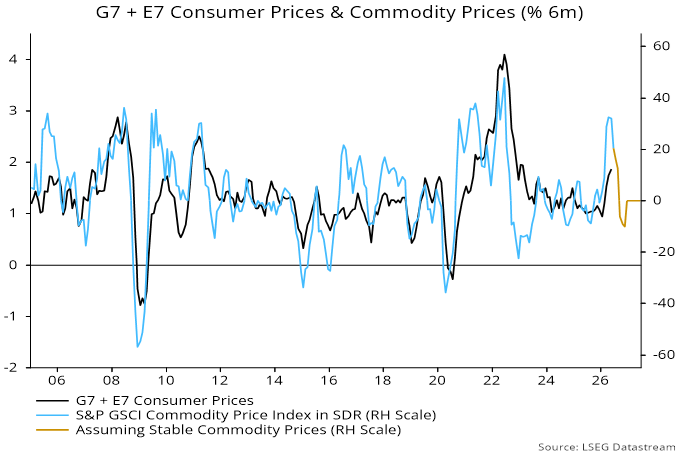
The real money slowdown reflected an energy-driven rise in six-month CPI momentum. This should reverse if recent commodity price relief is sustained – chart 3.

Chart 3

Chart 3 showing G7 + E7 Consumer Prices & Commodity Prices (% 6m)

Yield curves, however, remain higher than before Gulf conflict, reflecting tighter actual and expected monetary policies. Higher rates could dampen nominal money growth.

Meanwhile, solid June flash PMI results suggest that six-month industrial output expansion will hold up near term.

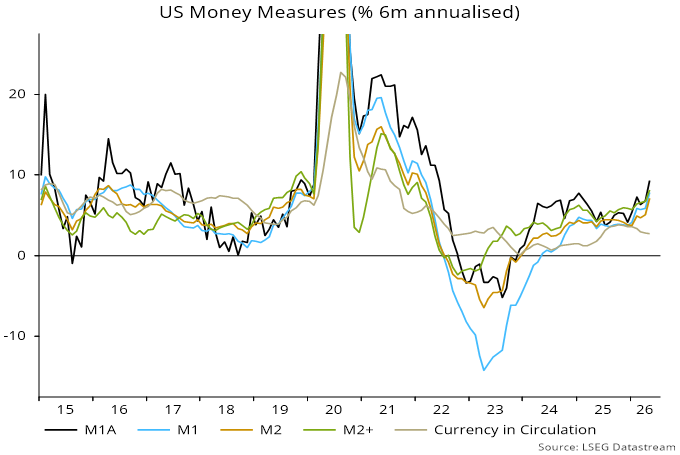
As previously discussed, global money growth has been supported recently by faster US expansion. Six-month growth of the preferred US narrow and broad measures here – M1A and M2+ respectively – rose further to 9.3% and 8.2% annualised respectively in May – chart 4. (The M1A series has been adjusted for a reclassification of some savings deposits as demand deposits in November.)

Chart 4

Chart 4 showing US Money Measures (% 6m annualised)

By contrast, six-month growth of Eurozone and UK broad money – as measured by non-financial M3 / M4 – was just 3.7% and 3.4% annualised respectively in April. May numbers are released next week.

The break-out of US six-month money growth above a January 2025 high coincided with a resumption of Fed balance sheet expansion. Chair Warsh wants to reverse this policy, suggesting a future downside risk to money trends.

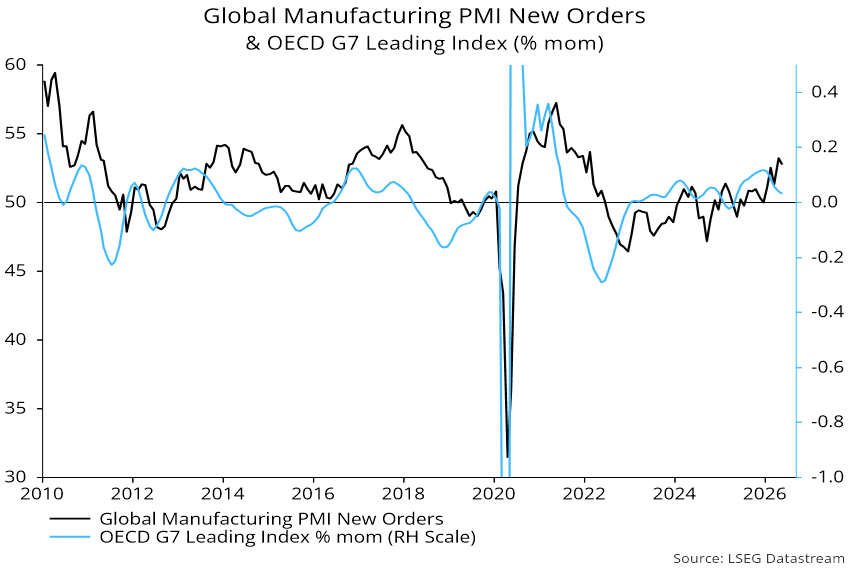
OECD leading indicator data and survey evidence on stocks support the forecast of a H2 loss of industrial momentum.

Global manufacturing PMI new orders edged down in May from April’s four-year-plus high. The expectation here has been for a further decline in H2, reflecting a slowdown in global six-month real narrow money momentum from a February peak – see previous post.

Two recent releases support this forecast. First, one-month growth of the OECD’s G7 leading indicator fell again in May. Growth peaked in December and has led PMI new orders by three months on average historically, suggesting that April’s orders high will prove lasting – see chart 1.

Chart 1

Chart 1 showing Global Manufacturing PMI New Orders & OECD G7 Leading Index (% mom)

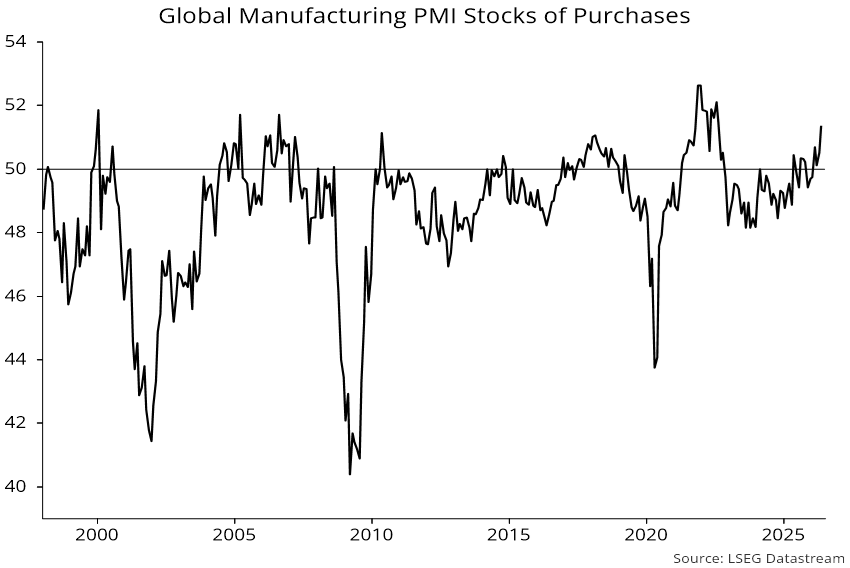
Secondly, the PMI stocks of purchases index indicates that stockpiling of inputs accelerated further last month, likely marking a cycle peak – chart 2.

Chart 2

Chart 2 showing Global Manufacturing PMI Stocks of Purchases

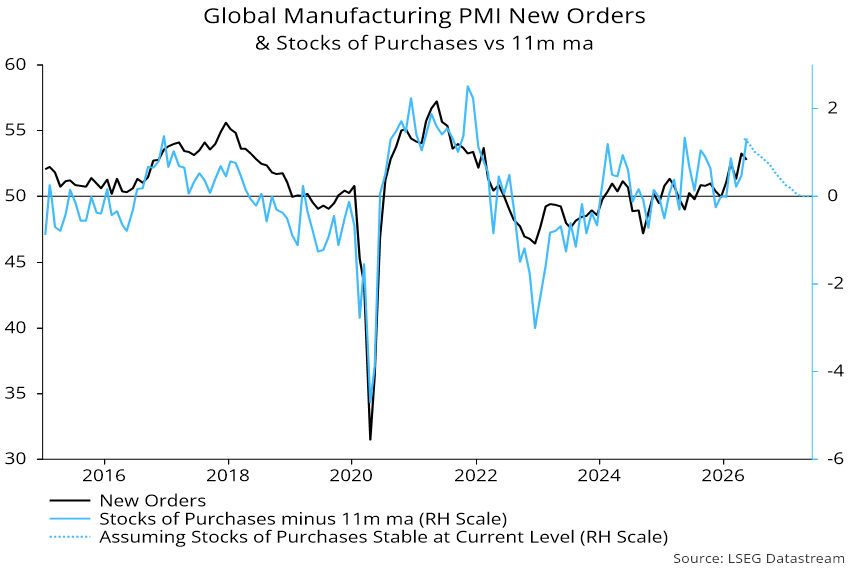
Growth in new orders is related to the rate of change of stockbuilding, implying a slowdown even in the unlikely event that the stocks of purchases index remains at its current extended level – chart 3.

Chart 3

Chart 3 showing Global Manufacturing PMI New Orders & Stocks of Purchases vs 11m ma

Eurozone and UK April money numbers signal rising recession risk and suggest that policy-makers should be considering easing not tightening.

Three-month annualised growth of Eurozone narrow money – as measured by non-financial M1 – slumped from 5.3% to 1.5% between January and April. UK growth fell from 3.8% to 0.7% over the same period, with a large contraction in April alone.

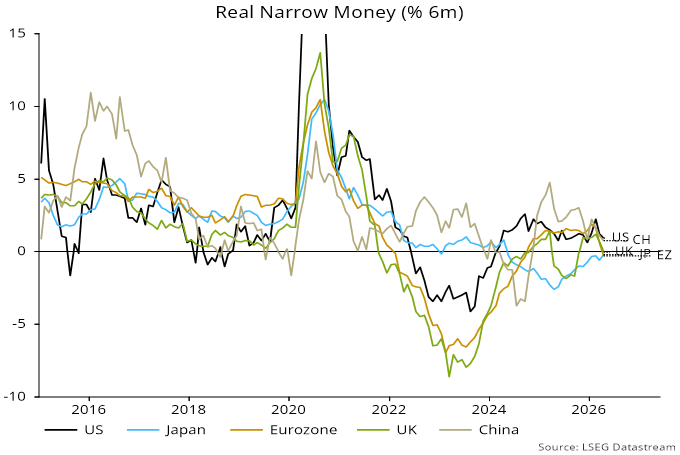
The nominal slowdowns compound a squeeze on real money from consumer price acceleration due to the Gulf War III supply shock. Six-month momentum of real narrow money fell to zero in the UK in April while turning negative in the Eurozone – see chart 1.

Chart 1

Chart 1 showing Real Narrow Money (% 6m)

Real money contractions have been a recession warning signal historically. An obvious push-back is that much greater weakness in 2022-23 was not reflected in a subsequent economic slump. Negative momentum was a misleading indicator of monetary conditions then because of a large overhang from the 2020-21 money growth surge. There is no such overhang now, so dismissing current weakness on the basis of that experience is dangerous.

Broad money trends are also worrying, with nominal growth of only 3.5% and 3.6% annualised respectively in Eurozone non-financial M3 and UK non-financial M4 in the three months to April. US broad money, by contrast, expanded at a 7.6% pace over the same period (M2+ measure).

Globally, six-month real narrow money momentum fell for a second month in April, supporting the forecast of a fall in manufacturing PMI new orders during H2 – chart 2.

Chart 2

Chart 2 showing Global Manufacturing PMI New Orders & G7 + E7 Real Narrow Money (% 6m)

An expected fall in global manufacturing PMI new orders suggests a moderation, at least, in current earnings strength.

New orders reached a four-plus-year high in April but DM flash results imply a pull-back in May. The forecast here is for a further decline in H2, reflecting an inflation-driven slowdown in global six-month real narrow money momentum from a February peak – see chart 1.

Chart 1

Chart 1 showing Global Manufacturing PMI New Orders & G7 + E7 Real Narrow Money (% 6m)

A further consideration is that orders have been boosted recently by demand front-loading and stockbuilding motivated by supply concerns, implying future payback.

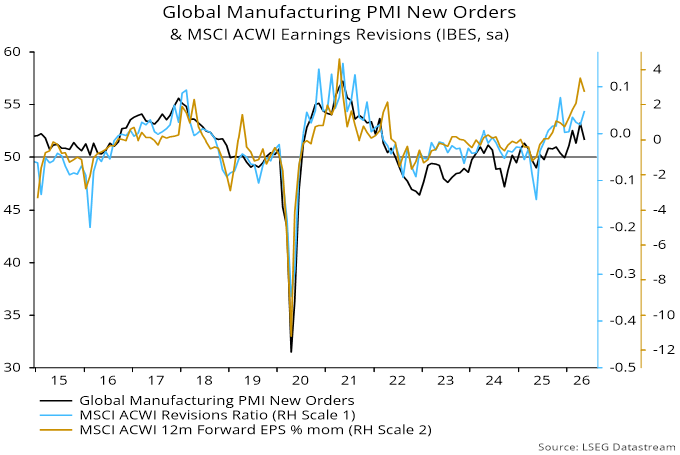
PMI new orders are contemporaneously correlated with MSCI World earnings revisions, whether expressed in terms of the revisions ratio (net proportion of analyst estimates upgraded each month) or the one-month percentage change in aggregate forecast earnings per share – chart 2.

Chart 2

Chart 2 showing Global Manufacturing PMI New Orders & MSCI ACWI Earnings Revisions (IBES, sa)

Both revisions measures remained strong in May but the expected new orders decline suggests a moderation, at least, ahead.

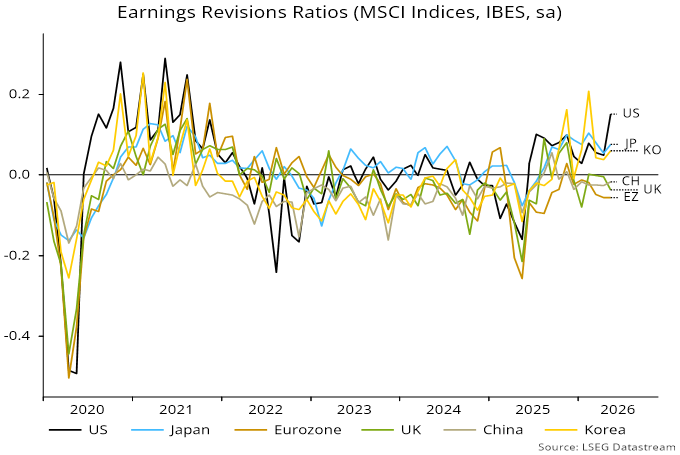
Current earnings strength is focused on the US and AI-spend beneficiaries, with downgrades in Europe, China and EM ex. Korea / Taiwan – chart 3. The suggestion of European relative weakness was echoed in the flash PMIs.

Chart 3

Chart 3 showing Earnings Revisions Ratios (MSCI Indices, IBES, sa)

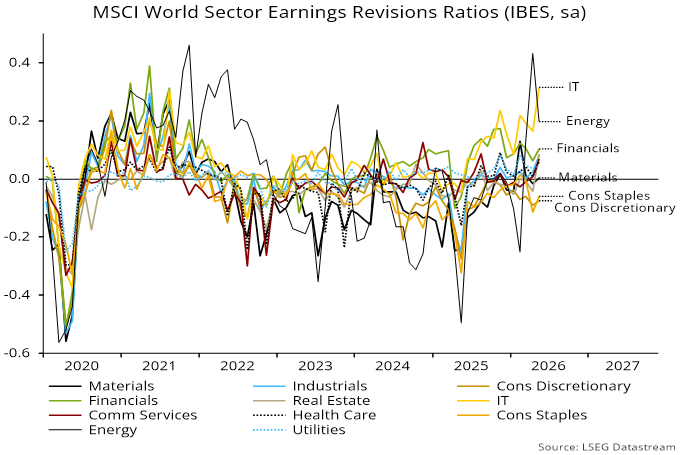
Sector wise, IT extended its lead, with consumer sectors continuing to suffer earnings downgrades – chart 4. The revisions ratio gaps between IT and consumer discretionary / staples reached new records in data extending back to 1995 – another manifestation of economic disparities.

Chart 4

Chart 4 showing MSCI World Sector Earnings Revisions Ratios (IBES, sa)

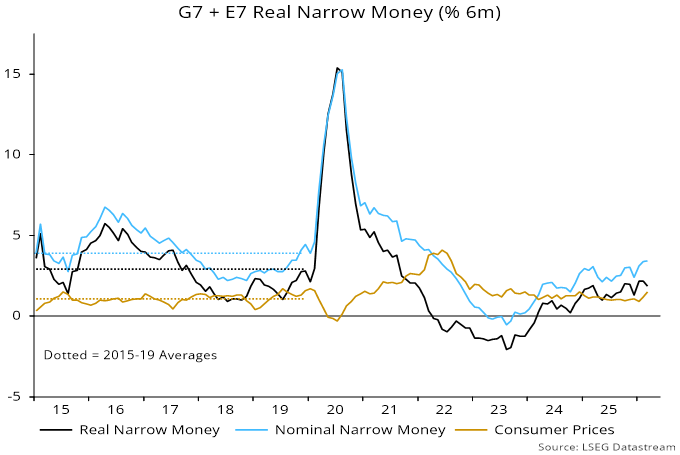
Global six-month real narrow money growth fell in March and is on course to decline further in April-May, suggesting a loss of economic momentum during H2.

The March fall from a four-plus-year high in January / February was due to a pick-up in six-month consumer price momentum, with nominal money expansion unchanged – see chart 1.

Chart 1

Chart 1 showing G7 + E7 Real Narrow Money (% 6m)

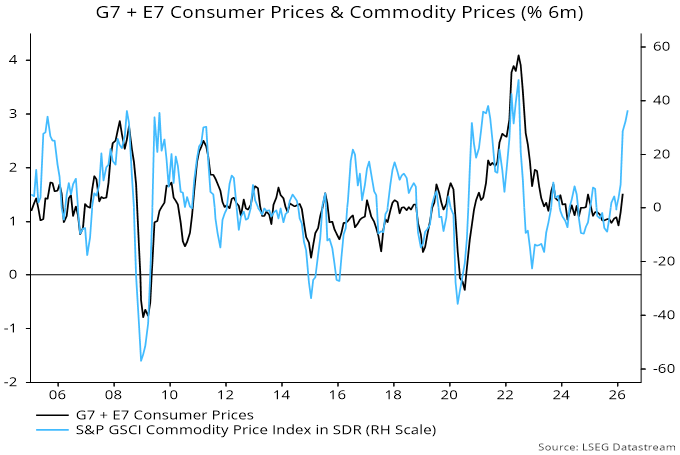
Commodity price strength implies a further increase in CPI momentum through May, at least – chart 2. So the slowdown in real money growth will extend unless nominal expansion accelerates – unlikely given recent upward pressure on rates.

Chart 2

Chart 2 showing G7 + E7 Consumer Prices & Commodity Prices (% 6m)

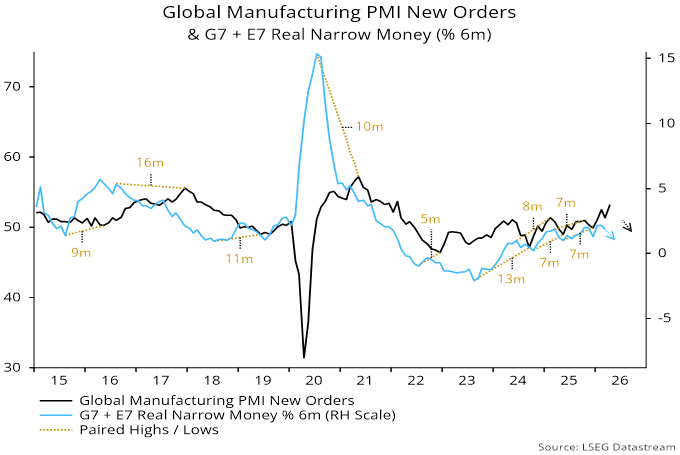
The earlier rise in real money growth has been reflected in a pick-up in global industrial momentum, with April manufacturing PMI new orders also the highest for four-plus years – chart 3. Orders have received an additional boost from precautionary stockpiling triggered by Gulf War III.

Chart 3

Chart 3 showing Global Manufacturing PMI New Orders & G7 + E7 Real Narrow Money (% 6m)

The lead time between turning points in real money momentum and PMI new orders has recently been running at seven months, suggesting a PMI reversal from September. The stockbuilding boost may have accelerated strength, however, implying an earlier peak.

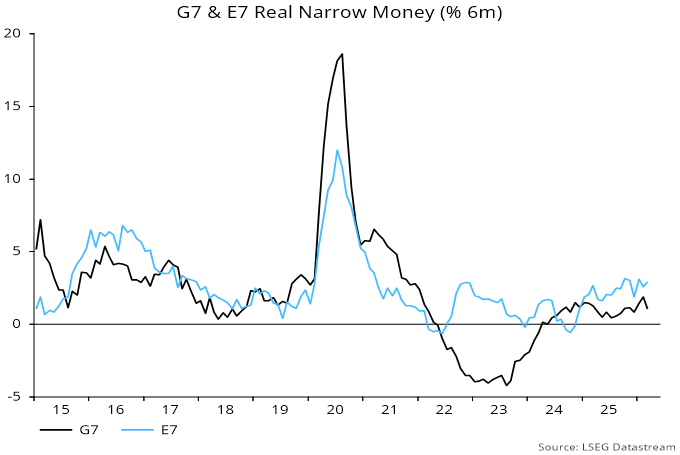
The March fall in global six-month real narrow money growth was driven by the G7 component, with E7 expansion tracking sideways – chart 4.

Chart 4

Chart 4 showing G7 & E7 Real Narrow Money (% 6m)

US growth fell in March but remains higher than in the rest of the G7 – chart 5.

Chart 5

Chart 5 showing Real Narrow Money (% 6m)

The March fall in global six-month real narrow money growth is estimated to have been accompanied by a similar slowdown in industrial output expansion, implying a continued small lead for the former – chart 6. The suggestion of “excess” money support for markets is consistent with recent equity market resilience.

Chart 6

Chart 6 showing G7 + E7 Industrial Output & Real Narrow Money (% 6m)

The expected further fall in real money growth, however, and near-term support for output from full order books, could result in the series converging or crossing soon.

The baseline view here has been that the global stockbuilding cycle would enter a downswing in 2026 into a low in H1 2027.

The stockbuilding cycle is a repeating fluctuation in the demand for production inputs and goods for final sale caused by inventories periodically over- and undershooting the level desired by manufacturers and distributors.

The approach here is to monitor the cycle using measures of the rate of change of G7 stockbuilding from national accounts data and business surveys.

The national accounts measure places the last cycle low in Q1 2023, implying that the current cycle is well-advanced – see chart 1.

Chart 1

Chart 1 showing G7 Stockbuilding as % of GDP (yoy change) & Business Survey Inventories Indicator

The business survey measure is more timely and recently crossed below zero, consistent with the cycle moving into a downswing.

The original research on the cycle – by Joseph Kitchin, published in 1923 – used data on commodity prices, bank clearings and interest rates. Kitchin attributed the cycle to “psychological causes”, making no explicit link with inventory behaviour.

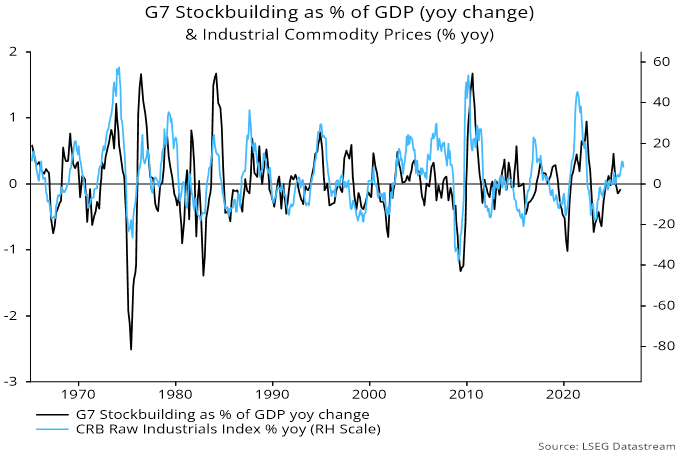
The cycle is evident in commodity prices because changes in demand for production inputs affect their price as well as volumes – chart 2.

Chart 2

Chart 2 showing G7 Stockbuilding as % of GDP (yoy change) & Industrial Commodity Prices (% yoy)

Tech investors often dismiss the cycle as an “old economy” phenomenon but electronic components are a key production input subject to the same inventory-related demand swings as traditional industrial commodities.

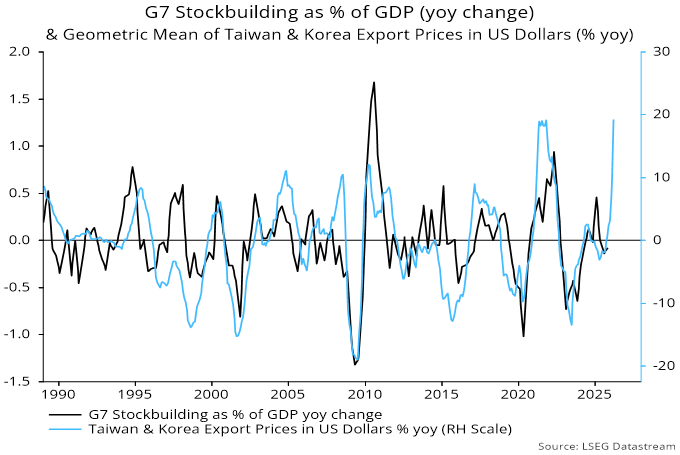
There is no single price index capturing the changing nature of electronic components. However, export prices of key supplier economies are a rough proxy. Chart 3 shows that the annual rate of change of an average of Taiwanese and Korean export prices in US dollars tracks the national accounts-based measure of G7 stockbuilding changes.

Chart 3

Chart 3 showing G7 Stockbuilding as % of GDP (yoy change) & Geometric Mean of Taiwan & Korea Export Prices in US Dollars (% yoy)

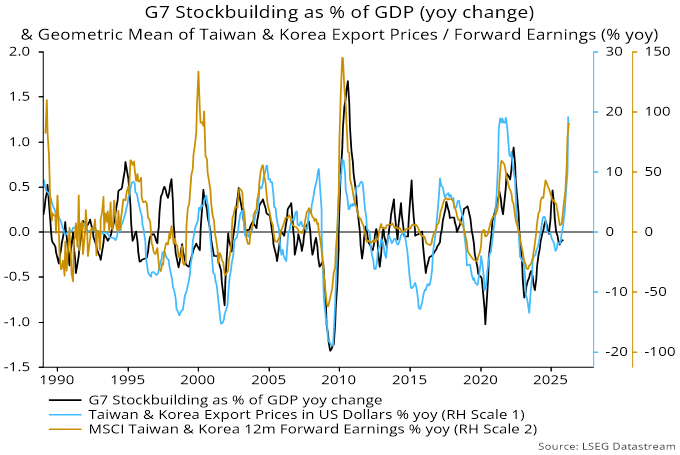
Chart 4 overlays the annual rate of change of an average of 12-month forward earnings estimates, showing a similarly significant correlation.

Chart 4

Chart 4 showing G7 Stockbuilding as % of GDP (yoy change) & Geometric Mean of Taiwan & Korea Export Prices / Forward Earnings (% yoy)

Based on the cycle assessment here, the implication is that momentum of component prices and earnings should be at or close to a peak.

Why could this prove wrong? One possibility is that the current stockbuilding cycle will extend. This cycle is judged to be the last of a set of five constituting the current housing cycle (which began in 2009). Final cycles tend to be longer than the 3.5-year average, with one recent example (1986-91) reaching 4.5 years. The next low, therefore, could be delayed until H2 2027, in turn suggesting a later start to the downswing.

Another counter-argument is that strong demand for components is being driven by an ongoing upswing in the business investment cycle – narrowly focused on AI-related spending in the current cycle – as well as peak stockbuilding. This cycle last bottomed in 2020 and has ranged between 7 and 11 years historically, so the upswing could – in theory – continue for several more years. The thinking here is that the current cycle is more likely to be short, reflecting a long prior cycle (11 years) and a drag from the expected stockbuilding downswing.