Why have markets gone “risk-off”? Two explanations are offered here.

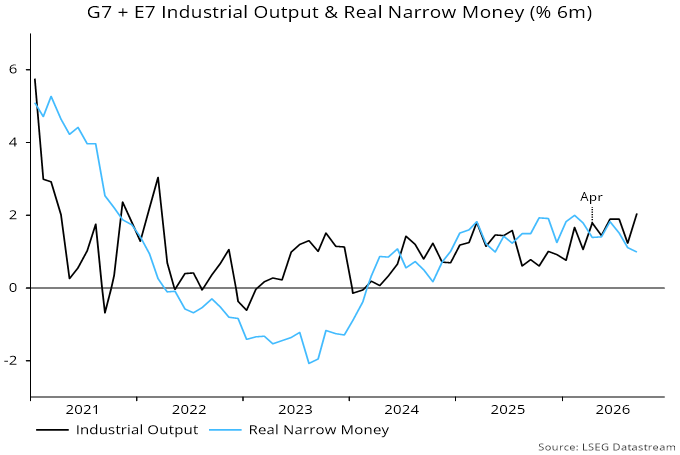
First, six-month growth of global real narrow money has been below that of industrial output since April, with the shortfall widening in September – see chart 1. A post in June suggested that the “excess” money backdrop had switched to being a headwind for equities.

Chart 1

Chart 1 showing G7 + E7 Industrial Output & Real Narrow Money (% 6m)

Historically, global equities outperformed US dollar cash by 12.0% pa on average when the real money / output growth gap was positive, underperforming by 5.5% when it was negative (based on data for 1970-2025 and allowing for a reporting lag).

A simple switching model based on this finding moved into cash at end-June, since when the MSCI World index has underperformed by 5.3% (as of yesterday’s close).

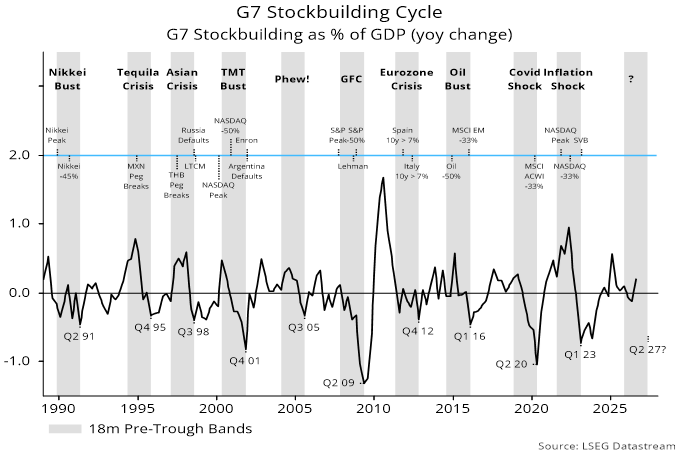
Secondly, the global stockbuilding cycle is judged to have reached a final peak in Q3 2026, with a downswing likely to extend into mid-2027, at least – see post from September. Markets typically experience a significant risk-off episode in the run-up to a cycle trough, often culminating in a “crisis” – chart 2.

Chart 2

Chart 2 showing G7 Stockbuilding Cycle G7 Stockbuilding as % of GDP (yoy change)

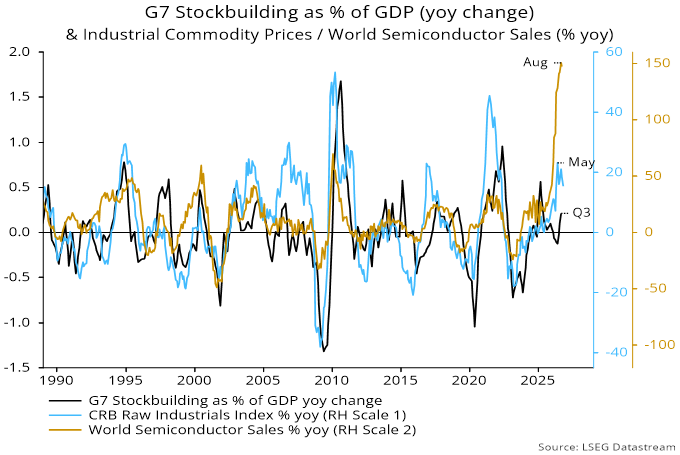
The cycle describes demand for production inputs – both raw materials and semi-manufactures, including electronic components – so exhibits a roughly contemporaneous correlation with their prices. The annual rate of change of industrial commodity prices has fallen since May, consistent with an incipient cycle downswing, while annual growth in global semiconductor sales may have peaked in August – chart 3.

Chart 3

Chart 3 showing G7 Stockbuilding as % of GDP (yoy change) & Industrial Commodity Prices / World Semiconductor Sales (% yoy)

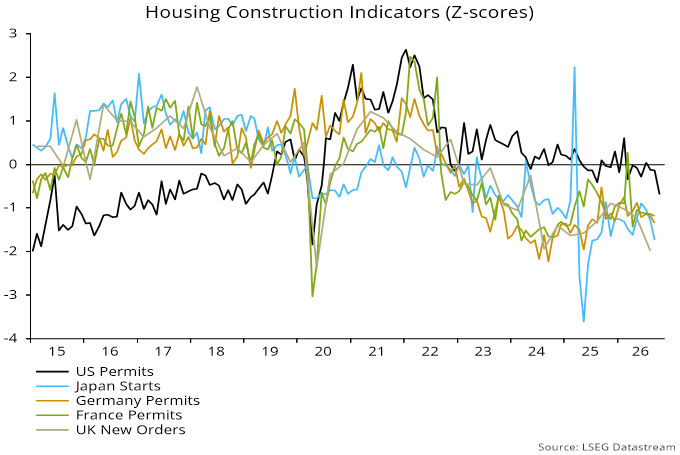
Equity market drawdowns in the run-up to stockbuilding cycle lows were usually significantly larger when the business investment and / or housing cycles were also weakening. The housing cycle is judged here to be in its late downswing phase, with a low possible between June 2027 and August 2028 – see the September post. Recent indicators are consistent with downside acceleration – chart 4.

Chart 4

Chart 4 showing Housing Construction Indicators (Z-scores)

October monetary data next week will allow an updated assessment of global “excess” money conditions.

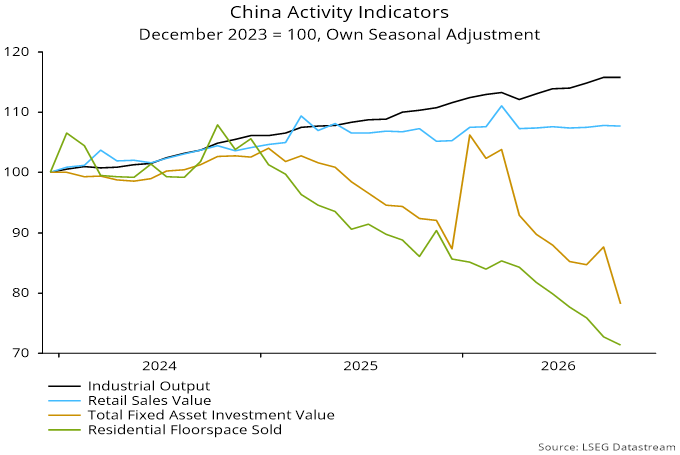
Chinese October activity numbers were worryingly weak, with industrial output / retail sales flatlining and fixed asset investment / home sales falling further – see chart 1.

Chart 1

Chart 1 showing China Activity Indicators December 2023 = 100, Own Seasonal Adjustment

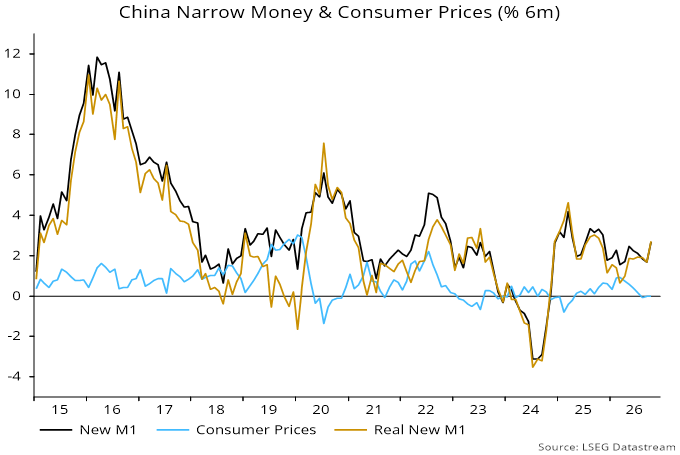
Monetary trends, however, offer a glimmer of hope. Six-month growth of real narrow money extended a recent recovery last month – chart 2.

Chart 2

Chart 2 showing China Narrow Money & Consumer Prices (% 6m)

The inclination here is to play down this improvement, for three reasons. First, the recovery partly reflects a fall in six-month consumer price momentum, which may prove temporary – chart 2.

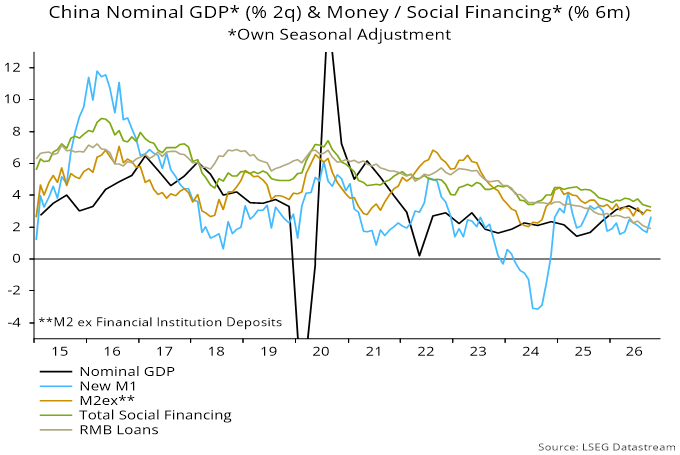
Secondly, stronger nominal narrow money growth has not been accompanied by a pick-up in expansion of the broad money measure tracked here, while credit aggregates continue to slow – chart 3.

Chart 3

Chart 3 showing China Nominal GDP* (% 2q) & Money / Social Financing* (% 6m) *Own Seasonal Adjustment

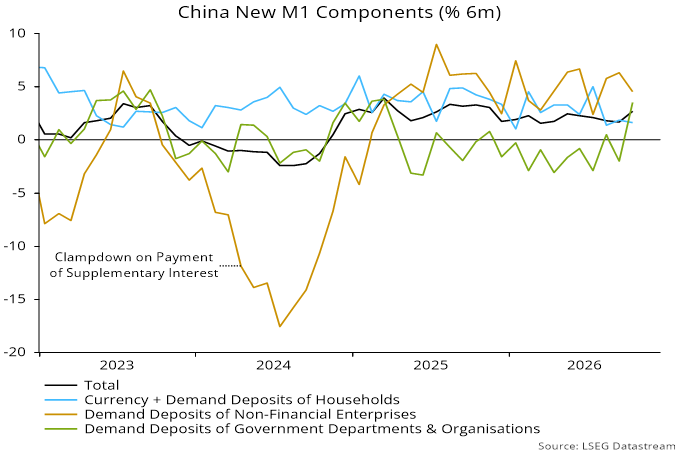
Thirdly, the rise in narrow money growth has been driven by increased demand deposit holdings of government-related bodies, with expansion of household and non-enterprise deposits little changed – chart 4. This is consistent with fiscal funds being deployed to ensure that the 2026 GDP growth target of 4.5% is achieved, raising the possibility of an unwind in early 2027.

Chart 4

Chart 4 showing China New M1 Components (% 6m)

Still, a further pick-up in narrow money growth into year-end would warrant a positive reassessment.

Illuminated night scene of Jioufen village in Taipei, Taiwan.

Over the last two weeks, our emerging markets team met with 30 technology companies across South Korea and Taiwan, covering semiconductors, memory, advanced packaging, testing, power equipment and cooling. Despite operating in different parts of the supply chain, most companies shared a similar message: demand is exceptionally strong, often exceeding available supply, with record backlogs and visibility extending well beyond historical norms.

Strong demand, cautious investors

A few observations stood out. A leading Korean memory maker expects shortages to persist through the end of the decade, while a major Korean electronic components manufacturer indicated that customers are financing more than half of their capacity expansions.

Among our emerging markets portfolio holdings, Chunghwa Precision Test Tech Co. Ltd. (6510 TT), a test interface supplier, is prioritizing higher-margin projects due to capacity constraints and indicated that its new capacity currently under construction is already fully booked. Acter Group Corporation Ltd. (5536 TT), an industrial engineering contractor specializing in cleanrooms, identified a shortage of engineers rather than orders as its main growth constraint.

Despite these strong fundamentals, investors we met during the trip were generally cautious. While 2027 is widely expected to be another strong year, concerns centred on the sustainability of AI-related spending beyond 2027, potential oversupply and whether current valuations adequately reflect these risks. This highlights an important distinction: strong corporate fundamentals and earnings visibility do not necessarily translate into attractive investment returns.

Since ChatGPT was launched in late 2022, AI adoption and infrastructure investment have accelerated significantly, benefiting a broad range of “picks and shovels” suppliers. However, the semiconductor industry has historically been cyclical. AI introduces a powerful new source of demand, but competition, capacity expansion and changes in customer spending still create cyclical pressures.

Capacity brings both opportunity and risk

At the same time, substantial new capacity in leading-edge foundry, advanced packaging and high-end memory has yet to come online. Our holding Eugene Technology Co. Ltd. (084370 KS), a Korean semiconductor equipment manufacturer, highlighted that increasingly complex memory manufacturing processes require more equipment per wafer, providing an additional source of equipment demand beyond growth in wafer production capacity.

Another development is the growing use of long-term agreements (LTAs) and customer prepayments to support capacity expansion. Our holding Kinsus Interconnect Technology Corporation (3189 TT), an advanced semiconductor substrate manufacturer, reported customer-funded equipment investments, and ISC Co. Ltd. (095340 KS), a Korean test socket manufacturer, which we also hold, expects LTAs to cover approximately half of its 2027 volumes. These contracts include minimum purchase commitments and compensation provisions but can be cancelled by mutual agreement. Such arrangements may reduce financial risks and improve visibility, but they do not guarantee future revenue or eliminate cyclical exposure.

A historical parallel

The telecommunications infrastructure boom around 2000 provides a useful historical comparison. The internet transformed the global economy, but many early infrastructure investors suffered from overcapacity and poor returns. The Fed’s monetary tightening in 1999–2000 also preceded the bursting of the technology bubble.

There are important differences today, particularly the stronger balance sheets of hyperscalers. Nevertheless, whether the substantial investments in AI infrastructure will generate adequate returns remains uncertain. Some neocloud providers also rely heavily on external financing. With the Fed having resumed rate increases in September 2026, tighter financial conditions could constrain their expansion or lead to financial distress, with implications for demand across the supply chain.

More capable, lower-cost AI models introduce another uncertainty. Greater efficiency could reduce computing requirements for individual applications, but also encourage broader adoption and potentially increase aggregate demand. Meanwhile, infrastructure spending remains concentrated among a relatively small number of hyperscalers.

AI could transform the global economy while generating disappointing returns for some investors. Strong near-term fundamentals do not rule out a downturn further ahead.

Holding two views at once

F. Scott Fitzgerald once noted that the test of a first-rate intelligence is the ability to hold two opposing ideas in mind simultaneously while retaining the ability to function. This observation is also relevant to investing. Research gives us the conviction to act, but we must remain open to evidence that challenges our conclusions. Even a well-supported investment thesis can be affected by unexpected developments, requiring us to reassess our views and adjust quickly.

We monitor whether easing shortages are accompanied by weaker order conversion, rising inventories or pressure on pricing and utilization. A combination of these developments would prompt us to reassess our investment thesis.

Ultimately, strong earnings do not guarantee attractive investment returns if already reflected in valuations, just as cyclical businesses can become attractive when expectations are excessively pessimistic. We cannot predict when the cycle will turn, but we can continue to evaluate new evidence, challenge our assumptions and adjust our investment decisions accordingly.

Street of historical center in Paraty, a preserved Portuguese colonial and Brazilian Imperial municipality in Rio de Janeiro, Brazil.

Brazil’s bull market collapsed as President Lula da Silva defied pollsters and prediction markets to win re-election in a run-off poll on the 25th of October. The result was a shock following the strong win in the first round by his right-wing opponent, Flávio Bolsonaro.

Lula is the first presidential candidate since Brazil’s return to democracy in the 1980s to come back from a first-round defeat. Falling abstention in the second round saw a wave of votes come Lula’s way in almost every municipality.
 

The market treated a probable Bolsonaro win as a certainty

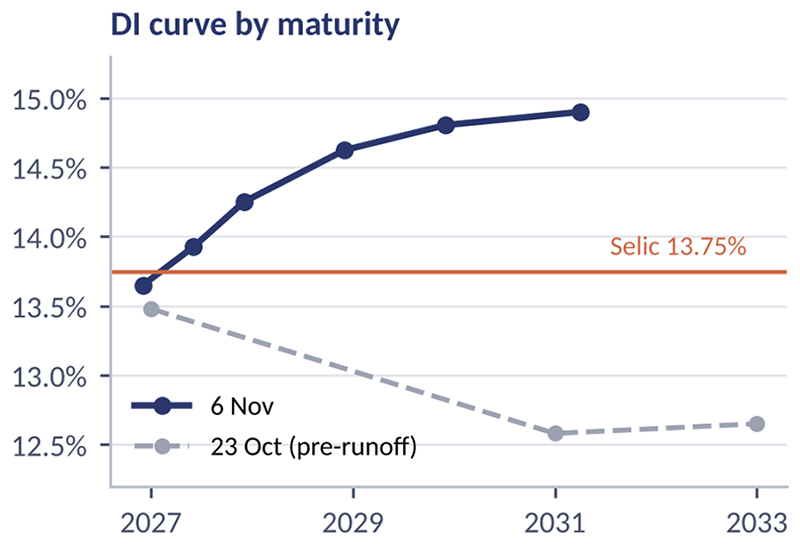
The rally in Brazilian equities after the first round on the 4th of October priced a change of government and a shift to conservative fiscal policy before it actually happened. The reality of a fourth term of Lula’s fiscal profligacy hit on Monday, the 26th of October, as the Ibovespa plunged 13.9% – the largest decline since March 2020. The Brazilian real had its worst day in 23 years and long rates rose by more than 250 basis points.

Forward interest rate curve reflects run-off surprise
 
A line graph depicting the forward interest rate curve after the results of the Brazil election.
Source: NS Partners & Bloomberg


Brazilian blackjack

Over the past year, we framed the investment opportunity in Brazil as akin to a game of blackjack where fiscal deficits, high interest rates and political uncertainty were the low cards favouring the dealer, and cheap valuations, resilient companies and the prospect of political change were the high cards. As the low cards come out of the deck, the investors’ odds gradually improve.


By August 2025, that “count” was becoming more favourable: economic resilience, easing inflation and increasingly credible prospects for a market-friendly political shift supported lifting exposure, while maintaining a strong bias towards quality companies.

The odds moved decisively in the investor’s favour in October 2026, when Flávio Bolsonaro’s unexpectedly strong first-round election result, combined with a major shift to the right in the Senate, raised expectations of fiscal consolidation and market-friendly policy.
 

Overweight into the first round

We went into the first round of elections with a modest overweight to Brazil (accounting for c.4% of the MSCI EM Index as at the 30th of September), which was well timed. Following a sharp rally, we decided to trim the exposure, focusing on businesses that were no longer as attractively valued, and recycled the profits into other LatAm countries.
 

Falling knife

Given Bolsonaro’s polling strength for the second round – the long-awaited “ace” of positive political change coming into view – we tilted the remaining exposure in Brazil towards higher beta names which would be more sensitive to falling rates.

Brazil’s Ibovespa tanked in the immediate aftermath of Lula’s victory, with the higher beta portion of our exposure underperforming. For these companies we were happy to wait for a bounce before selling in order to de-risk and move underweight Brazil. Higher quality businesses with ROIC well above the cost of capital, strong balance sheets, dollar revenues and less leverage to the economy were retained.

There is no appetite here for mechanically buying the dip as the risk-reward proposition has changed dramatically in our view. The bulls argue that Lula has campaigned as a socialist but governed as a pragmatist in the past and that we should expect the same this time around. This is debatable and the reality today is that the starting conditions for Lula’s fourth term are different:

  • Public debt is above 80% of GDP, having risen by more than 10 percentage points over Lula’s third term.
  • Less than 8% of the federal budget is adjustable due to mandatory spending.
  • Lula’s rhetoric and campaign commitment signals a more expansionary policy regime, with increased pension expenditure, welfare commitments and proposed debt-relief programs.
  • This is likely to pressure inflation higher, which has not been tamed by a Selic policy rate of 13.75%.
  • Highly indebted households and corporates are already struggling with rising debt servicing costs.

 
The outlook for Brazil has changed, and thus a collapse in equity prices does not automatically signal a buying opportunity.
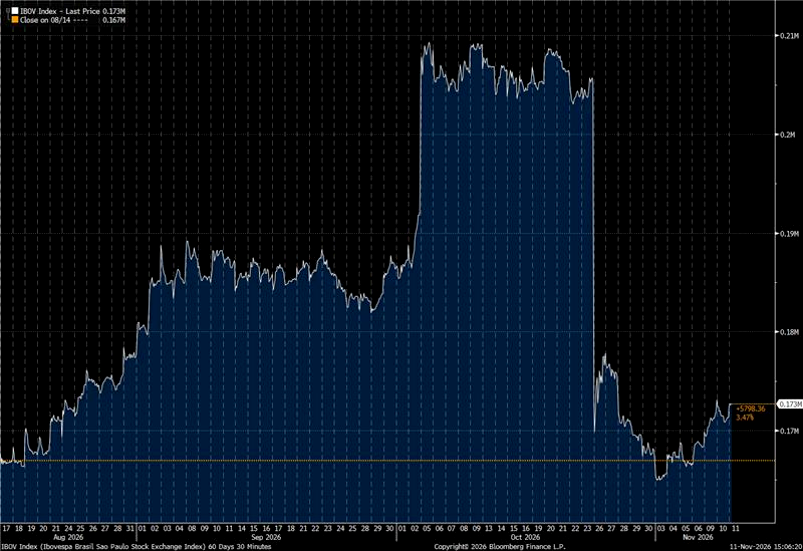
As you can see below, the market remains above its level 60 days ago when polls suggested a tight election. This hardly screams “bargain” to us.

Ibovespa Index – last 60 days
 
Line graph illustrating the Ibovespa Index over the last three months.
Source: Bloomberg


The regional picture for LatAm ex-Brazil is attractive

Reducing exposure in Brazil is also a matter of opportunity cost. As a region, Latin America trades on c.10x forward earnings versus 14x for emerging Asia, the widest discount since 2010. Trailing earnings are up 22% year on year and ROE is over 18% with a dividend yield of nearly 5% (Bradesco BBI, October 2026).

Unlike Brazil, the political backdrop for the rest of the region is more favourable. Market friendly right-wing governments lead 9 out of 20 countries versus six in January 2023, which includes Argentina and Peru where the portfolio has banking, IT and energy exposure.

Mexico is a notable exception, led by left-wing president Claudia Sheinbaum. She has proven to be a more pragmatic leader than her socialist predecessor AMLO and has managed US-Mexico relations well with an eye to supply chain “nearshoring” opportunities, while seeking to secure a relatively positive outcome from USMCA negotiations. A favourable trade deal would be a tailwind for Mexican equities exposed to renewed investor confidence and compliant exporters integrated into US supply chains.

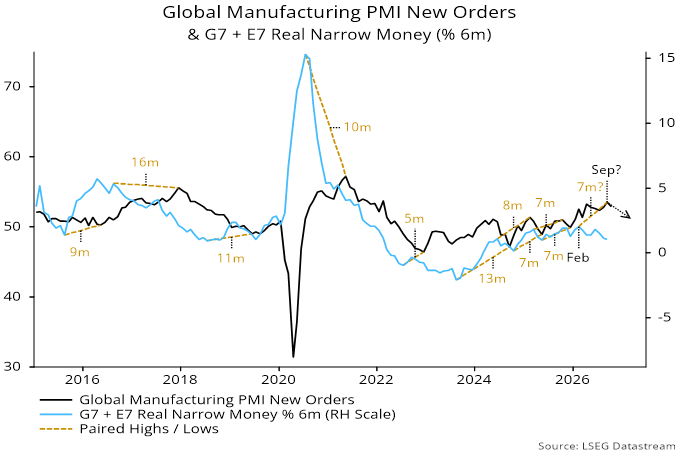
Previous posts suggested that a fall in global six-month real narrow money momentum since February would be reflected in a decline in manufacturing PMI new orders from around September, based on a recent seven-month lead at turning points. Orders cooled on schedule in October – see chart 1.

Chart 1

Chart 1 showing Global Manufacturing PMI New Orders & G7 + E7 Real Narrow Money (% 6m)

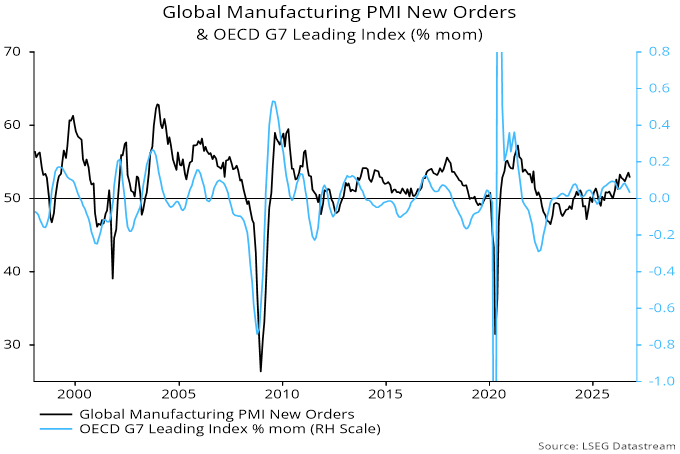
Two other developments support the conjecture that September marked a significant PMI peak. First, monthly momentum of the OECD’s G7 leading index slowed for a third month in October. The index has displayed a short lead on PMI new orders historically, although initial results are often revised – chart 2.

Chart 2

Chart 2 showing Global Manufacturing PMI New Orders & OECD G7 Leading Index (% mom)

Note that the leading indices for six of the G7 countries exclude any measure of money (Canada is the exception), so the recent slowdown represents independent corroboration of the monetary signal.

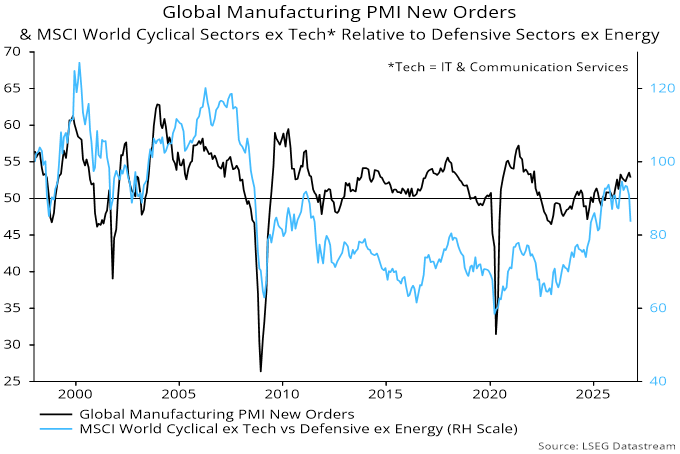
Secondly, the October PMI pull-back has been accompanied by sharp underperformance of equity market cyclical sectors versus defensive sectors. Similar-sized moves in the cyclical relative historically were associated with sustained / significant PMI declines – chart 3.

Chart 3

Chart 3 showing Global Manufacturing PMI New Orders & MSCI World Cyclical Sectors ex Tech* Relative to Defensive Sectors ex Energy *Tech = IT & Communication Services

A key principle of the monetary approach followed here is that money growth in excess of the needs of the economy flows into markets, pushing up prices.

A rising tide of “excess” money need not lift all boats. Investors will crowd into “themes” backed by a fundamental story. Such themes vary across cycles.

A popular theme will sustain outperformance while the flow of excess money continues, unless the underlying story breaks.

Conversely, a shift to deficient money will be associated with a liquidation of exposure to such themes, resulting in their underperformance. Unloved investments that attracted little of the prior money flow are less at risk and may benefit from position unwinds and / or “safe haven” buying.

Equity market behaviour this year illustrates these ideas. The proxy measure of global excess money used here – the difference between six-month rates of change of real narrow money and industrial output – switched from positive to negative in April, a development known by mid-June (allowing for reporting lags).

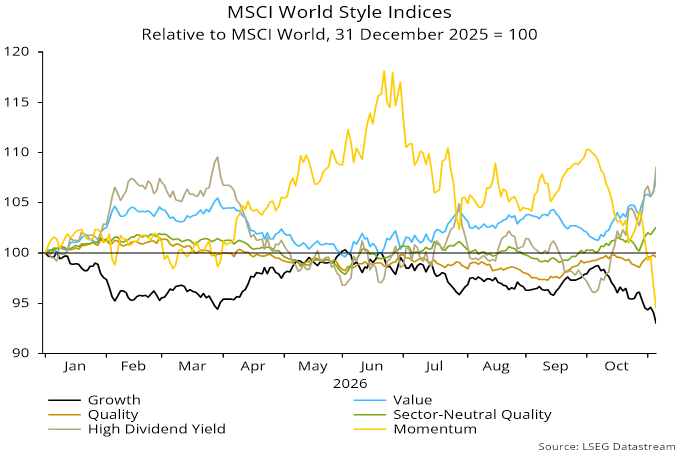
The MSCI World momentum index outperformed strongly during H1, peaking with a 18.1% relative gain versus MSCI World on 22 June. It has since swung to a 5.6% loss – see chart 1.

Chart 1

Chart 1 showing MSCI World Style Indices Relative to MSCI World, 31 December 2025 = 100

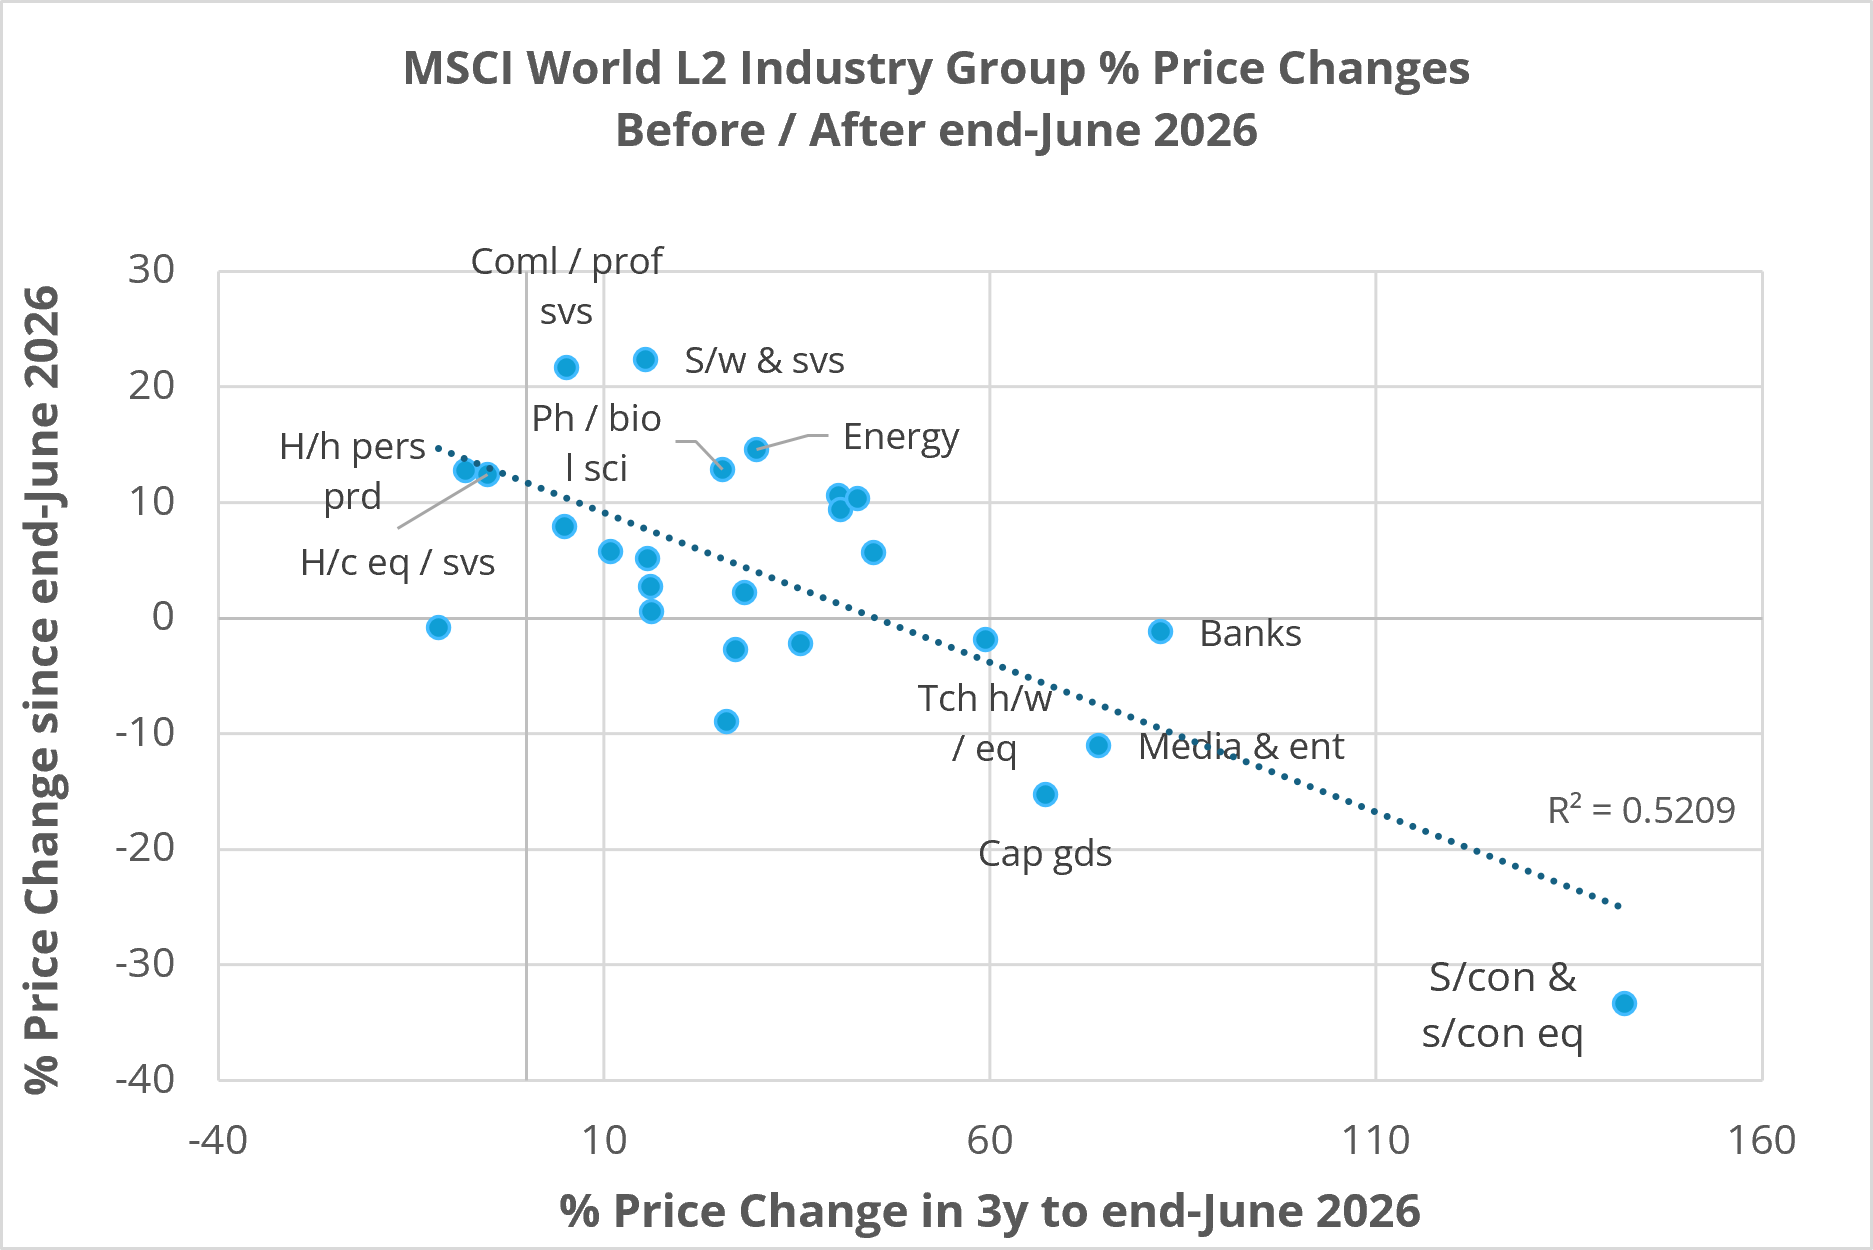
The reversal in the former speculations of choice is also apparent in L2 industry group data. Industry price changes since June have been negatively correlated with performance over the prior three years – chart 2.

Chart 2

Chart 2 showing MSCI World L2 Industry Group % Price Changes Before / After end-June 2026

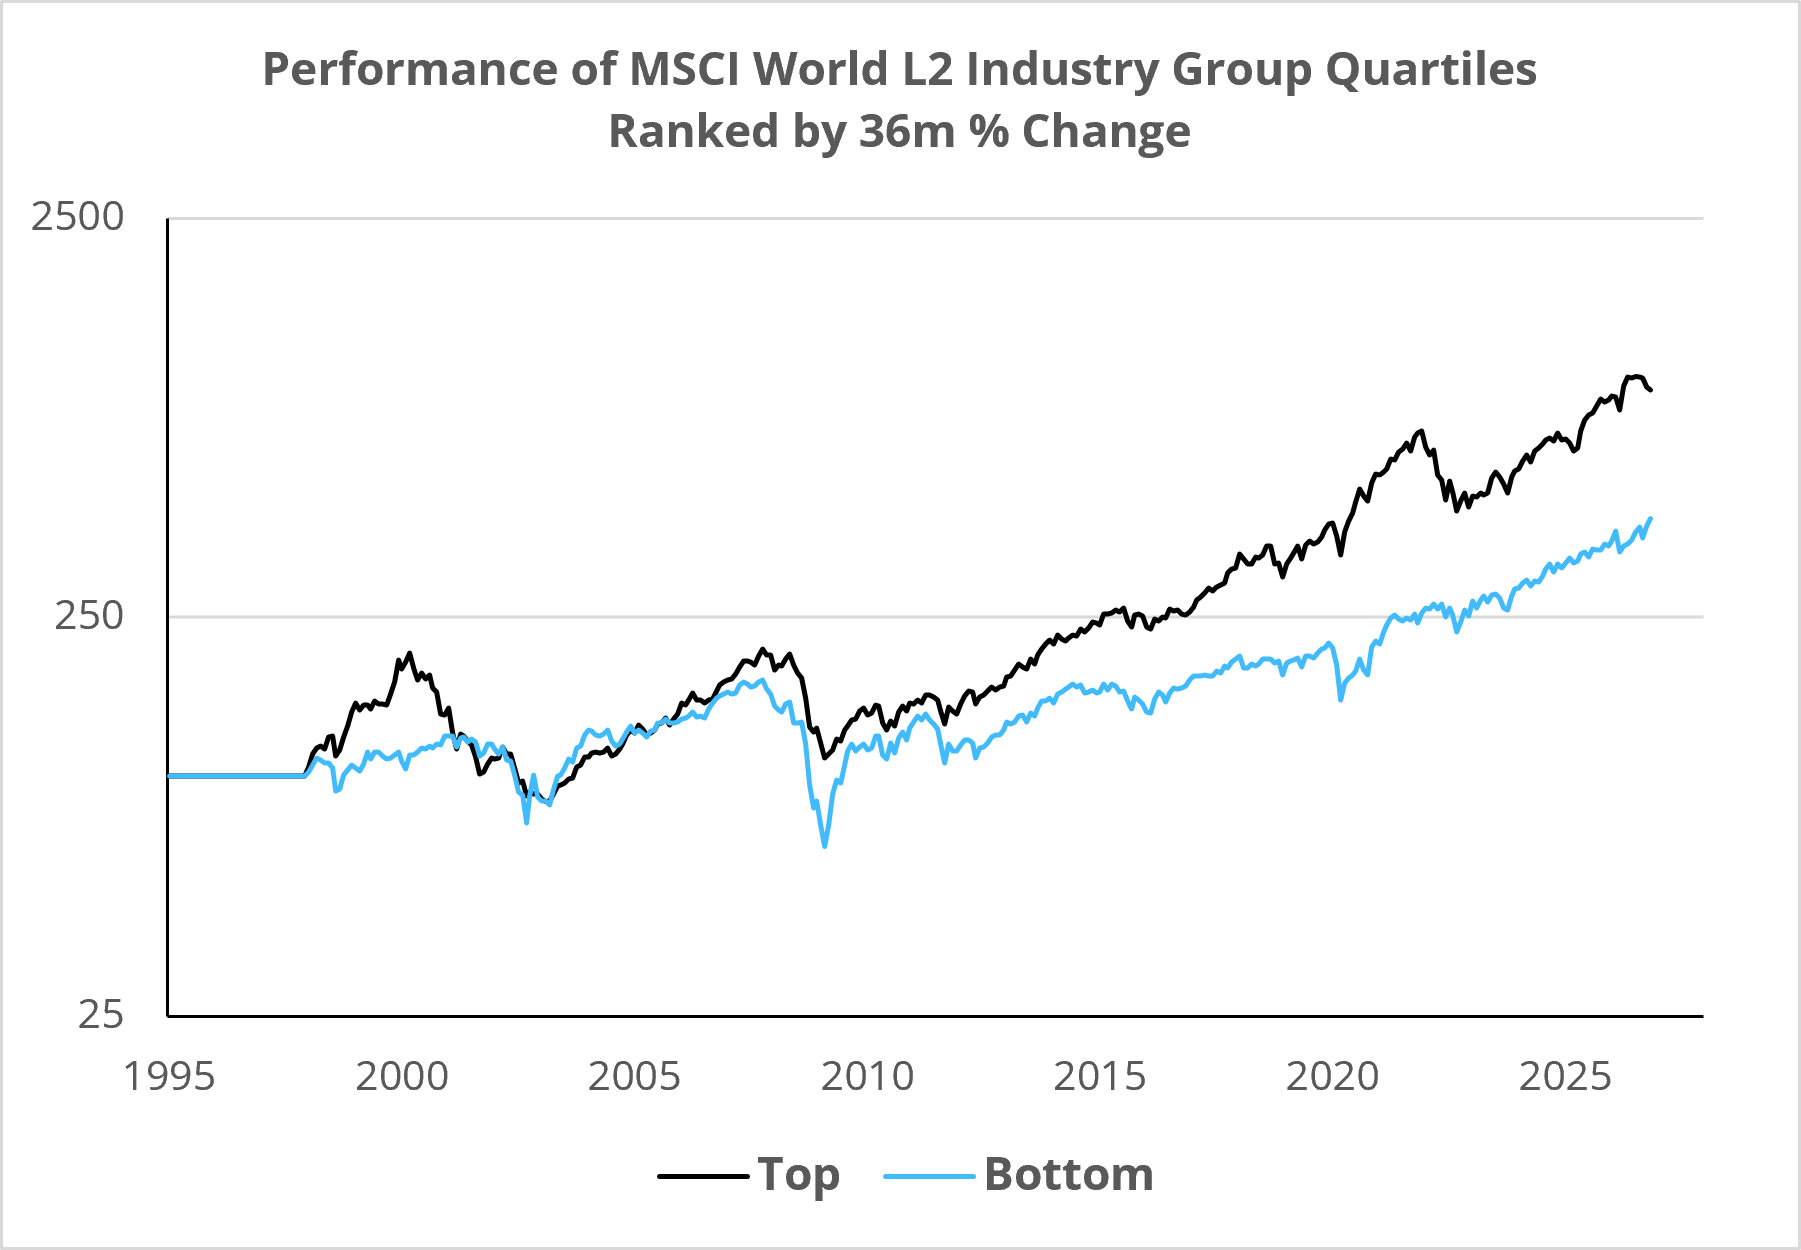
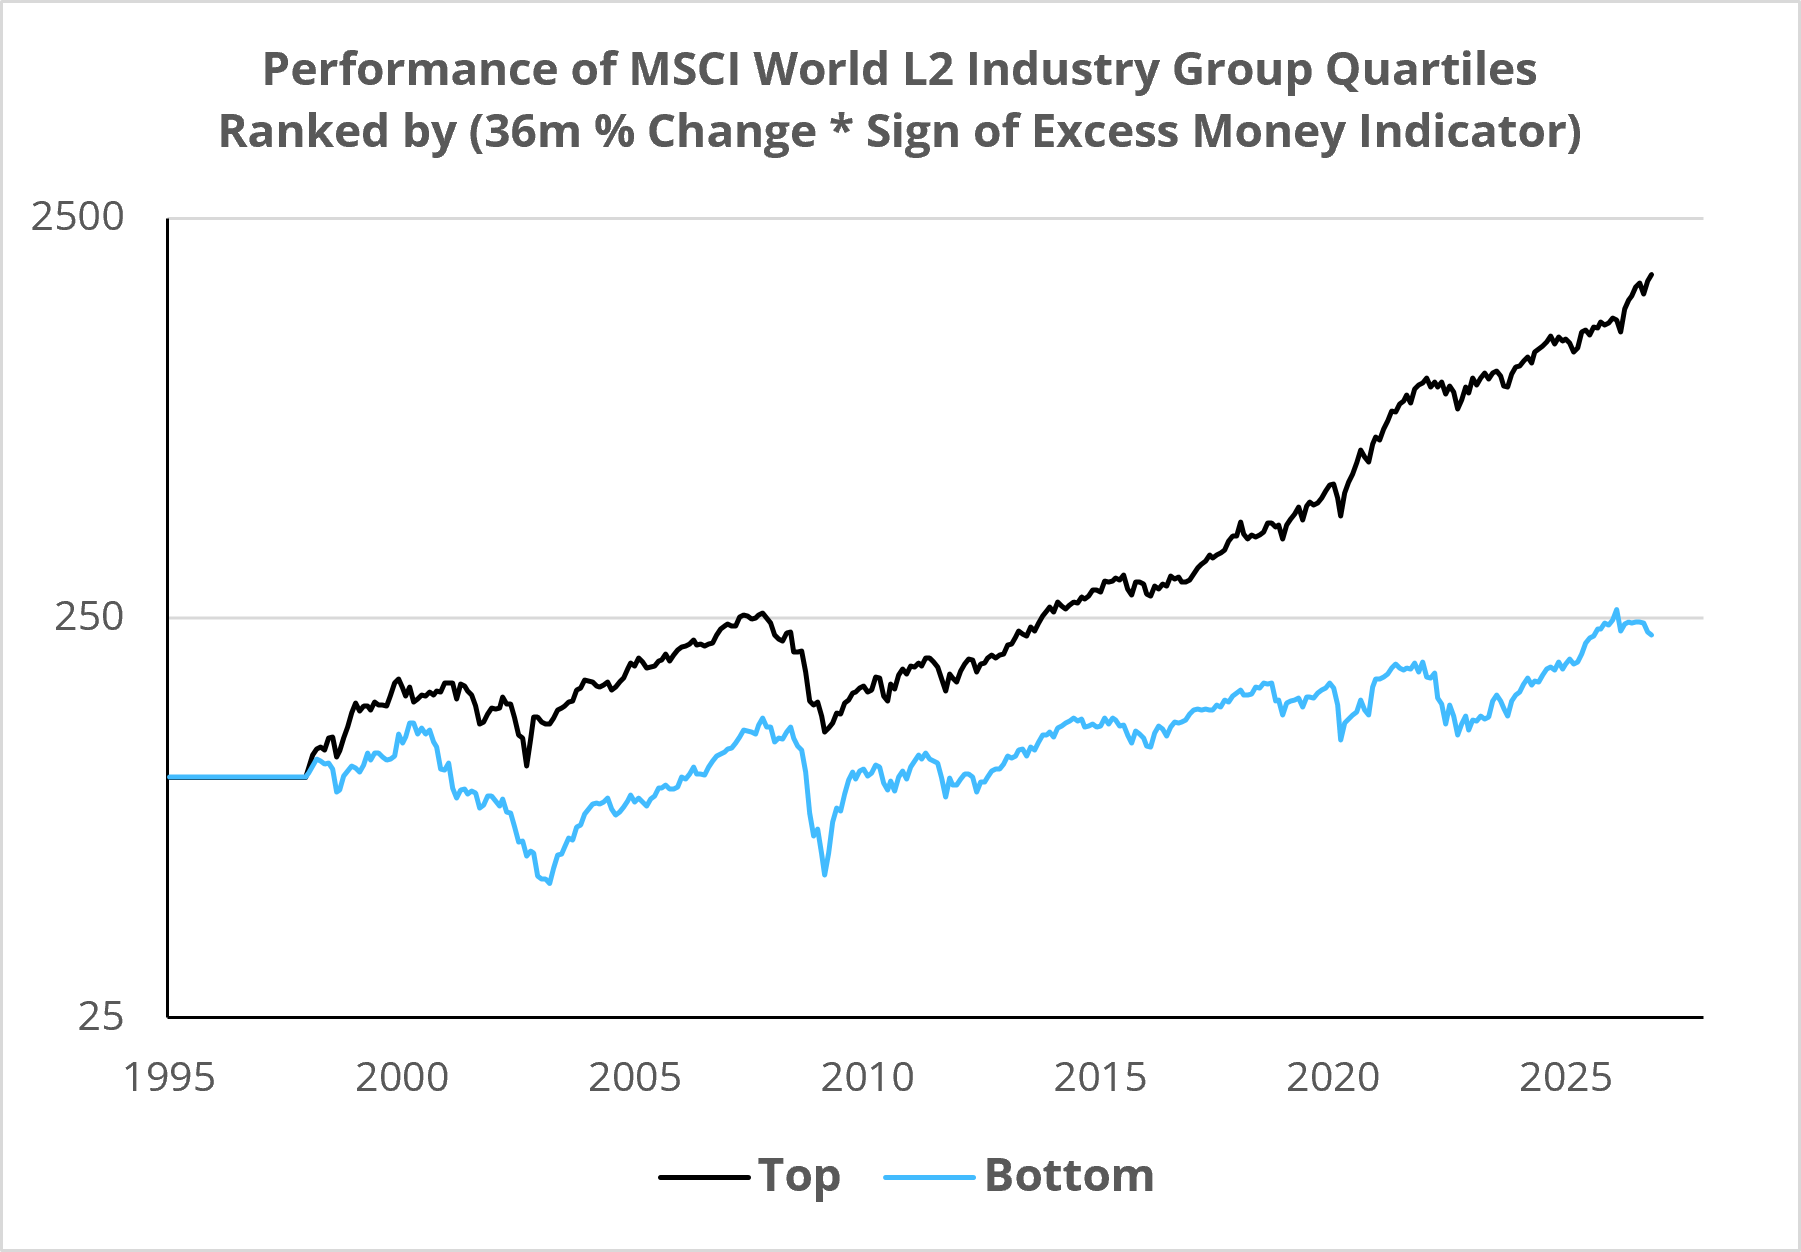
Consider a simple investment strategy of 1) separating industry groups into quartiles based on performance over the prior three years and 2) going long the top quartile and short the bottom quartile. Such a momentum strategy would have outperformed since 1998, when three-year performance data start – chart 3.

Chart 3

Chart 3 showing Performance of MSCI World L2 Industry Group Quartiles Ranked by 36m % Change

Now consider modifying this strategy by following it only when the global excess money indicator is positive, adopting the reverse approach – going short the outperformers and long the laggards – when the indicator turns negative. The modified strategy would have generated stronger and more consistent performance – chart 4.

Chart 4

Chart 4 showing Performance of MSCI World L2 Industry Group Quartiles Ranked by (36m % Change * Sign of Excess Money Indicator)

Momentum has worked as an equity investment style historically but this may partly reflect a prevalence of favourable excess money conditions. The addition of a monetary overlay could result in superior risk-adjusted returns.

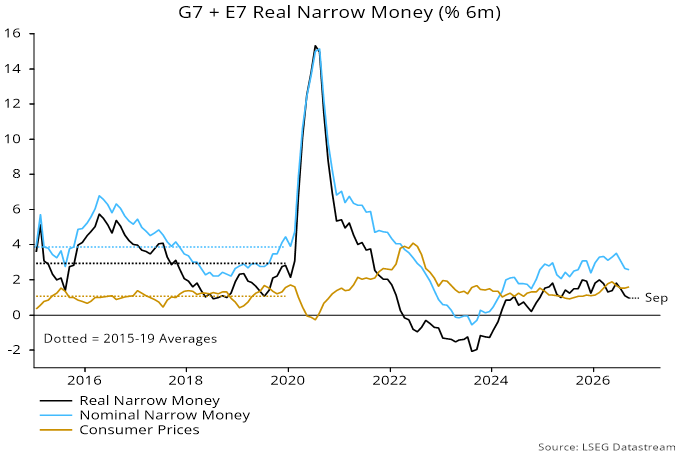
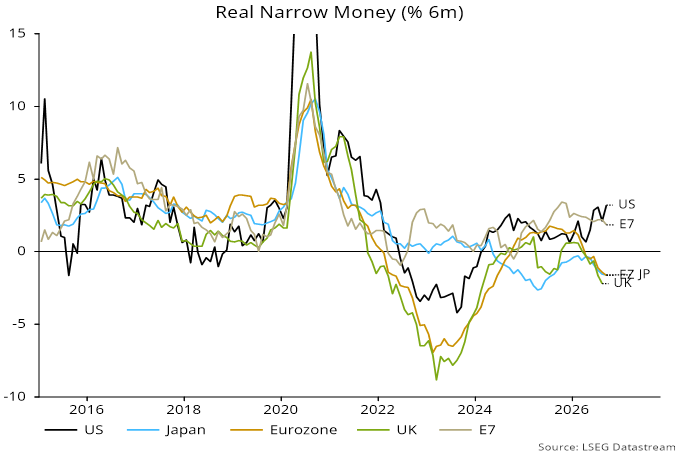
Additional information confirms that global six-month real narrow money momentum eased further in September but the decline was smaller than projected in a post last week, reflecting a surprise rebound in the US component to a new high – see charts 1 and 2.

Chart 1

Chart 1 showing G7 + E7 Real Narrow Money (% 6m)

Chart 2

Chart 2 showing Real Narrow Money (% 6m)

The decline in the global measure from a February peak signals a loss of economic momentum in late 2026 / early 2027 but the current indication is for cooling rather than significant weakness.

The September fall in global momentum was driven by faster contractions in Japan and the Eurozone coupled with a slowdown in the E7 component – chart 2.

The further widening of the US / rest of G7 differential suggests US relative economic strength and misaligned monetary policies, with the Fed behind the curve but the ECB and Bank of Japan already in overrestrictive territory.

Broad money trends echo this message, with US M2+ rising at a 7.5% annualised rate in six months to September versus growth in Japanese M3 and Eurozone non-financial M3 of 0.8% and 3.0% respectively.

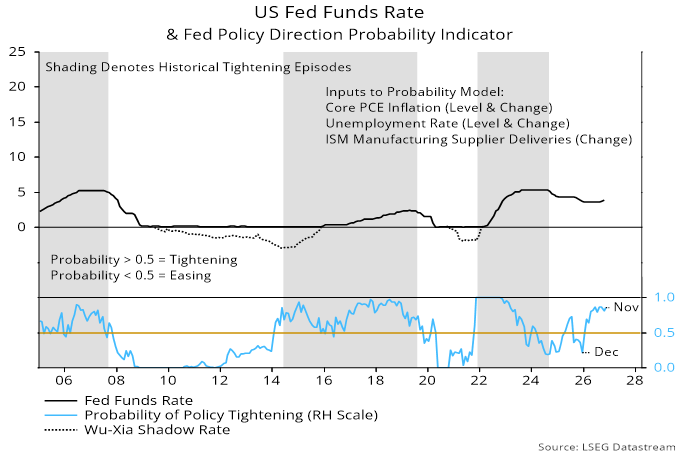
Fed officials – with the possible exception of Chair Warsh – give no weight to monetary signals but coincident economic indicators that have informed policy decisions historically also imply a need for tightening. The simple Fed model followed here estimates the probability of a further hike at 86%, based on current and lagged values of the unemployment rate, annual core PCE inflation and the ISM manufacturing delivery delays indicator – chart 3.

Chart 3

Chart 3 showing US Fed Funds Rate & Fed Policy Direction Probability Indicator

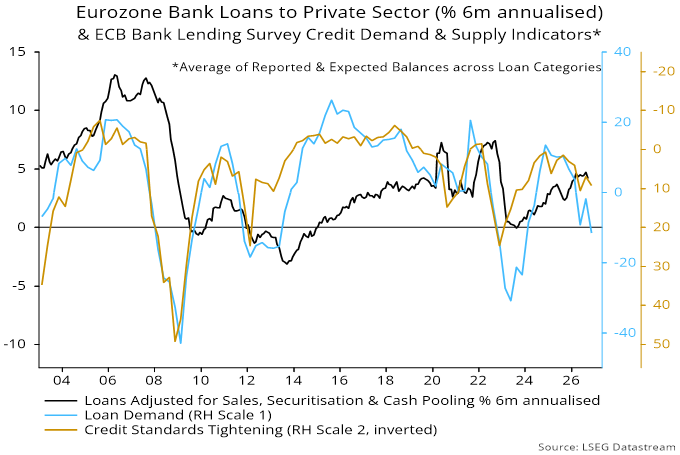
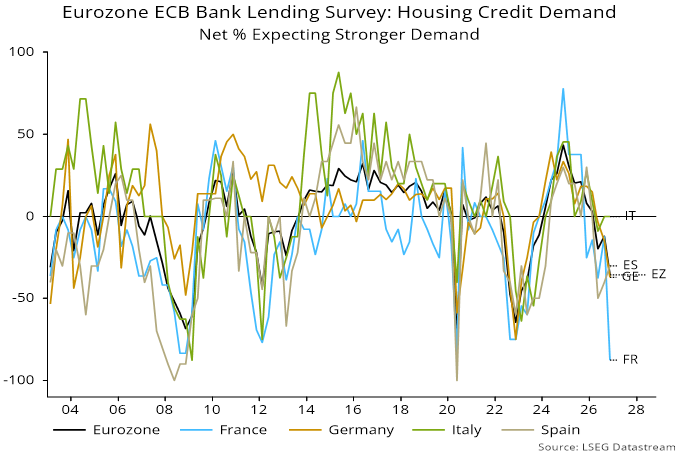
The monetary message of deteriorating Eurozone economic prospects, meanwhile, is supported by the ECB’s Q4 bank lending survey, showing a fall in credit demand balances across loan categories, led by housing – chart 4. French expected housing credit demand plunged to a record low, with the German balance also weaker and Spanish lenders remaining downbeat – chart 5.

Chart 4

Chart 4 showing Eurozone Bank Loans to Private Sector (% 6m annualised) & ECB Bank Lending Survey Credit Demand & Supply Indicators* *Average of Reported & Expected Balances across Loan Categories

Chart 5

Chart 5 showing Eurozone ECB Bank Lending Survey: House Credit Demand Net % Expecting Stronger Demand

Various pins connected by a blue string, representing a digital network and information sharing.

Investors spend enormous amounts of time and energy trying to forecast the future, whether it is the direction of interest rates, inflation, economic growth or market valuations. Yet markets have a way of surprising even the most informed investors. While a portfolio built on a correct forecast can deliver impressive results, consistently predicting the future is another matter entirely. However, could the benefit of more data, more computing power and general advances in artificial intelligence (AI) be a game changer?

The forecasting trap

Most investment committee meetings eventually arrive at the same debate: rates, inflation, economic growth and the direction of markets. While these questions matter, they can create a false sense of certainty. The danger is not in making forecasts, but in becoming too dependent on them. When portfolios are positioned around a base case expected outcome, investors are effectively making a bet that the future will cooperate. Unfortunately, markets rarely feel obligated to do so.

Few predicted the Global Financial Crisis. Few anticipated the scale of pandemic-related disruptions. Few foresaw the speed of the inflation surge that followed the pandemic and the aggressive interest rate response from central banks. Forecasts are attempts to navigate an uncertain future. They are most valuable when they challenge our thinking, highlight potential risks and test assumptions. Forecasts should shape the discussion, not dictate the decision. AI may help investors make better forecasts, but its greater value lies in improving how forecasts are developed, challenged and used. The most significant opportunity may be to facilitate better quality decisions in the face of uncertainty.

Decision-making quality

Decision-making quality is the thoroughness of the thinking and process behind a decision, independent of whether the eventual outcome turns out well or badly. This distinction is particularly important in investing because good decisions can produce bad outcomes, and bad decisions can produce good outcomes, especially over short periods.

Consider two investment committees. The first makes a concentrated investment based on a strong conviction about how the future will unfold. The forecast proves correct, the position performs exceptionally well, and the decision is celebrated as a success. The second committee takes a different approach. It rigorously evaluates assumptions, considers alternative scenarios, evaluates potential risks, and chooses a more diversified path. Markets move in unforeseen ways and short-term results disappoint.

Looking at only the outcome, the first decision appears superior. But did the committee actually make the better decision? Not necessarily. Chance, timing and unpredictable events often play a larger role than we care to admit when it comes to outcomes.

From a governance perspective, it is more clear-cut. The process adopted by the second committee, assessing whether the portfolio could withstand a wide range of outcomes, demonstrated higher decision-making quality. Moreover, sound decision-making processes tend to be more repeatable than accurate predictions. That is why many of the world’s leading institutional investors spend less time trying to be right and more time ensuring they make informed, high-quality decisions, regardless of what the future brings.

How AI can help

AI has the potential to improve forecasting and decision-making quality in several important ways.

  • Improve the information going into the decision. The most obvious is the sheer amount of information it can process. Historically, forecasts were constrained by what an investment team could reasonably read, analyze and model. AI can expand that field dramatically, incorporating market data, economic indicators, company results, earnings-call transcripts, news and other forms of information.
  • More information is only part of the story. AI can also identify complex, unstructured and non-linear relationships that investors might overlook. And unlike a traditional forecasting exercise that can become focused on a particular point of view, an AI-supported process can continually reassess the evidence as latest information becomes available.
  • Challenge the investment thesis. A powerful role of AI is its ability to function as a systematic devil’s advocate. Investment teams naturally build convictions around their views. AI can provide a disciplined counterweight by actively searching for evidence that challenges those views, surfacing information that may have been discounted, and questioning how the thesis could turn out to be wrong. As the latest information emerges, it can also highlight what has changed since the original view was formed.
  • Surface behavioural biases. AI can function as a broader disciplined challenge to the reasoning behind an investment recommendation, helping identify how behavioural biases may influence the decision. By systematically surfacing alternative interpretations, counterarguments and overlooked evidence, AI can encourage investors to separate what they believe from why they believe it. The goal is not to eliminate human judgment, but to make that judgment more balanced and defensible.
  • Bring institutional memory into the process. AI can help teams search for previous investment cases, research and decision records to see if there was a similar decision before, what the assumptions were then and how it played out. This turns organizational knowledge into something more usable at the point of a new decision being made.

AI has limitations too. Much of what it learns comes from relationships contained in existing information, while markets can change precisely because something happens that does not resemble the past. The greater opportunity for AI lies in strengthening forecasting discipline: drawing on a broader range of information, challenging assumptions more rigorously, updating views more quickly, and recognizing sooner when the world has moved on.

Improving decision-making discipline

Even with better tools and more information, uncertainty cannot be eliminated from investing. The payoff from AI is not simply better forecasts, but better-quality decisions by strengthening the human process that surrounds it: challenging the objective, interrogating the evidence, widening the alternatives, stress-testing uncertainty, exposing potential biases and questioning whether the rationale is truly defensible. These following six questions provide a practical way to challenge your thinking, evaluate your assumptions and bring greater discipline to the decisions that matter.

  1. Objective: Are you clear about the objective? High-quality decisions start with clarity of purpose. If we are not clear about the outcome we are trying to achieve, it becomes difficult to judge the alternatives, understand the trade-offs or determine whether the decision was successful.
  2. Information: Are you using the most relevant information available? High-quality decisions depend on having relevant information, not simply more information. The goal is to identify what genuinely matters to the decision, separate useful evidence from noise, and recognize where important gaps remain.
  3. Alternatives: Have other courses of action been considered? Decisions rarely come from choosing whether to accept the first idea on the table. Good decision-making means deliberately considering diverse ways of achieving the objective before deciding which path offers the best balance of opportunity, risk and trade-offs.
  4. Uncertainty: Have you considered what could happen rather than relying on a base case forecast? The future rarely unfolds exactly as expected. Rather than building a decision around a base case forecast, a range of plausible outcomes should be assessed to challenge whether the decision still makes sense if the future looks different from the base case.
  5. Behavioural biases: Have you recognized the risk of potential behavioural biases? Even with clear objectives and valuable information, our judgment can still be influenced by how we interpret that information. We naturally bring prior experiences, existing beliefs and preferences to a decision.
  6. Process: Is there a clear rationale for defending the decision if the outcome disappoints? Because outcomes are influenced by uncertainty, even a well-reasoned decision can produce a disappointing result. A strong process creates a clear record of why we made the decision, what was believed, what alternatives were considered and what risks were knowingly accepted.

Together, these questions will not guarantee a good outcome, but they can significantly improve the quality of the decision behind it and help ensure that it was thoughtful, disciplined and made for the right reasons. AI can play distinct roles across these questions. For some, it can actively help develop the answer by analyzing information, exploring alternatives or testing outcomes. For others, its value may be as a disciplined reminder to challenge our thinking and ensure an important consideration has not been overlooked.

Leveraging AI for better quality decisions

The objective is not AI replacing human judgment when making decisions. It is better human judgment, supported by AI. Markets contain too much uncertainty for investors to judge skill simply by whether a decision was right. A better approach tries to build a disciplined process for making quality decisions by challenging assumptions, surfacing contrary evidence, identifying biases, considering alternative scenarios and making the reasoning behind a decision more explicit. The real promise of AI may not necessarily be making investors materially better at predicting the future, but to allow them to arrive at better quality decisions irrespective of what the future holds.
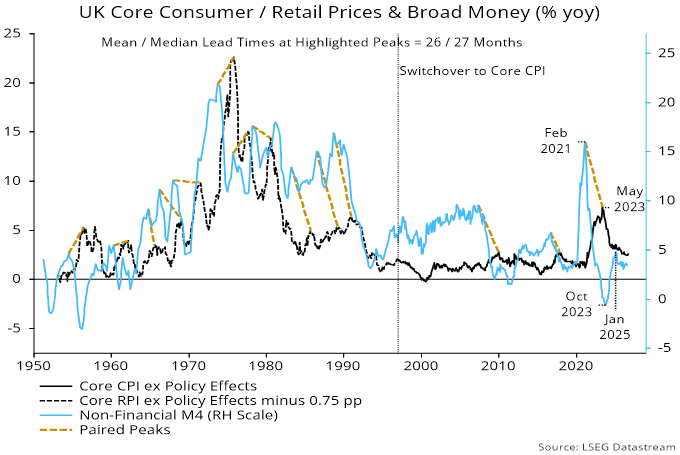
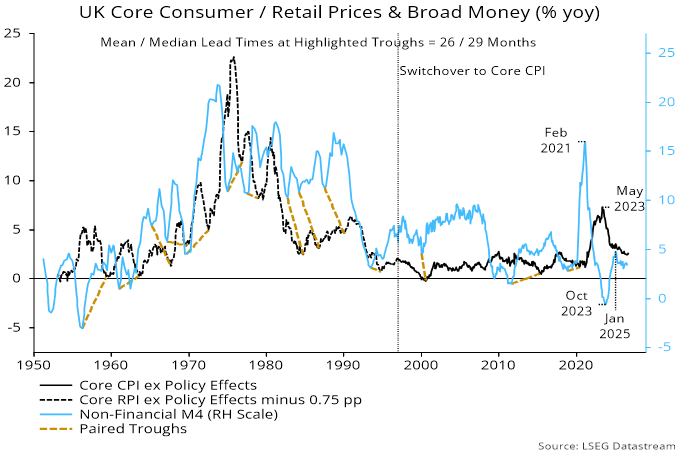
Turning points in UK annual broad money growth have led those in annual core CPI / RPI inflation by a median 28 months in the post-war period – 27 months at peaks and 29 at troughs. Charts 1 and 2 show the paired highs and lows used to calculate these averages.

Chart 1

Chart 1 showing UK Core Consumer / Retail Prices & Broad Money (% yoy) Mean / Median Lead Times at Highlighted Peaks = 26 / 27 Months

Chart 2

Chart 2 showing UK Core Consumer / Retail Prices & Broad Money (% yoy) Mean / Median Lead Times at Highlighted Troughs = 26 / 29 Months

The annual rate of change of broad money – as measured by non-financial M4 – bottomed in October 2023. Based on the median lead, a previous post suggested that annual core inflation would trough by March 2026.

The low, instead, was reached in April at 2.5%, with the core rate moving sideways over the summer, rising to 2.8% in September.

The level at the low was significantly higher than had been expected here. Disinflationary pressure from extreme monetary weakness in 2023 was offset by cost-push shocks from government policies and now Gulf War III.

How long will the current upswing last?

The recovery in money growth from the October 2023 low was minor and short-lived. Annual expansion peaked at 4.8% in January 2025. Allowing for the median lead of 27 at peaks, this suggests a core inflation top around April 2027.

Annual broad money growth subsequently fell to a low of 3.0% in January 2026, remaining weak through August (3.4%). Monetary effects, therefore, should be pushing down on inflation during H2 2027 and into 2028.

Additional policy tightening now would reinforce this trend, risking unnecessary damage to the economy and an eventual inflation undershoot.

Fish being examined under a microscope for scientific research and food quality control.

The trade relationship between Canada and the United States has recently been making news and is among the largest in the world, with more than USD1 trillion in annual trade in goods and services. Agricultural and farm goods are always at the heart of discussions as the divide is philosophical. The US philosophy favours regulation in a free-market structure, while Canada sacrifices free market for income stability as found in the case of dairy farm quotas.

Regulatory differences affect competitivity. In the example of food additives, Canada generally requires pre-market approval by Health Canada before an additive may be used in food. The United States also regulates additives through the Food and Drug Administration (FDA), but permits the “Generally Recognized as Safe” (GRAS) framework, which allows ingredients to enter the market without the same formal review process. This has led to perceptions that Canada applies a more precautionary approach to food regulation. Small changes in regulations can affect farmer and grower profitability significantly.

The good news

North America is changing; dietary guidance in both Canada and the United States has shifted toward promoting whole foods and limiting highly processed foods. The next twenty years of food regulation may look much more like health-care regulation. Future regulators are increasingly likely to focus on metabolic health, chronic disease, nutritional quality and ingredient transparency. The food industry could experience a transformation similar to what happened with tobacco decades ago: not outright prohibition, but progressively tighter restrictions on ingredients perceived to contribute to long-term health costs. The resulting shift toward “food as medicine” may become one of the most important secular themes in agriculture, nutrition and health care.

Over the next decade, food safety regulators across the globe will increasingly focus on ultra-processed foods, food additives and dyes, sugar content, antibiotic use in livestock and nutritional labeling.

Raising the standards on raising proteins

These regulatory trends also apply to proteins, which are often affected by antibiotics and pesticide usage where regulations differ greatly by region.

As an example, Norway is generally considered the world’s most advanced and stringent salmon regulator. Amongst other measures, the country:

  • Enforces strict sea-lice thresholds,
  • Uses a “traffic-light” system that can limit industry growth if environmental impacts become excessive, and
  • Explicitly incorporates wild salmon health into licensing decisions.

Norway has effectively said growth is permitted only if environmental performance improves.

These standards benefit companies that participate in the salmon industry via closed containment systems, sea-lice technologies, vaccines or aquaculture automation. This has allowed Norway to become the leading producer of high-quality salmon globally.

SalMar ASA (SALM NO) is the world’s second-largest Atlantic salmon producer. Headquartered in Frøya, Norway, the company operates a highly cost-efficient, vertically integrated aquaculture model spanning broodstock, smolt, ocean farming and processing. It sells to over 50 countries worldwide.

SalMar’s production footprint covers:

  • Norway (Central & Northern): The foundational engine representing the vast majority of its volume.
  • Iceland: Operates through its majority-owned subsidiary, Icelandic Salmon.
  • Scotland: Runs a 50/50 joint venture via Scottish Sea Farms.
  • SalMar Ocean: Its pioneering offshore and open-sea aquaculture division.

SalMar holds extensive unutilized capacity within its current operational licenses. Driven by exceptional biological performance (such as superior fish survival and growth rates), SalMar raised its full-year 2026 harvest guidance to 350,000 tonnes, marking a sharp 16% year-over-year volume increase from 2025. The company anticipates scaling this existing organic footprint further to reach 378,000 tonnes by 2028.

Agricultural pesticides

In agriculture, pesticide regulation can drastically affect the competitive landscape. This is evident when border regions grow similar produce such as California and Mexico.

Mexico has taken a strict stance against highly hazardous pesticides (HHPs). The country has banned over 180 pesticides that remain legally authorized in the United States, including systemic adjustments to phase out glyphosate. On the other side of the border, while California permits the use of certain chemicals banned in Mexico, it severely restricts how and when they can be applied (e.g., rigid tracking of drift, groundwater protection zones and strict worker re-entry intervals).

The California Department of Pesticide Regulation annual marketplace surveillance reports consistently shows that 97% to 98% of California-grown produce is completely compliant or features non-detectable residues. It is imported produce that dynamically accounts for a disproportionate volume of illegal pesticide residue violations.

For Mexican avocados and lemons to enter the US market legally, they must comply with US EPA pesticide residue tolerances. While Mexican avocados generally test clean because their thick, unconsumed skins shield the fruit, other Mexican citrus crops (like limes and lemons) occasionally trigger border enforcement actions due to traces of unapproved or excessive pesticides.

Global Alpha is invested in Limoneira Company (LMNR US), a diversified global agribusiness and land management corporation headquartered in Santa Paula, California.

Founded in 1893, they manage roughly 14,500 acres of agricultural land. Limoneira controls extensive global supply chains by sourcing citrus across the United States, Chile, South Africa and Mexico to ensure year-round supply for retail and foodservice buyers. Beyond pure farming, the company holds high-value, adjudicated water rights and operates a profitable real estate development arm.

Limoneira is undergoing a core business model transformation designed to unlock hidden asset value and shift capital into higher-margin segments.

Limoneira is aggressively shifting underutilized land into avocado production to capture robust, multiyear US demand growth. Avocado farming boasts superior unit economics over standard lemons. Driven by 400 acres planted in 2023 and 2024 finally reaching commercial maturation, management projected avocado production to exceed 10 million pounds in fiscal year 2027 – representing an ambitious 30% volume expansion. The company aims to add another 500 avocado acres by the end of 2027.

US trade case against Chinese choline

As food regulations increase, discrepancies between countries will multiply trade disputes and antidumping (AD) cases. In June 2026, a petition was filed alleging that Chinese producers were benefiting from Chinese government subsidies and dumping choline salts into the US market at unfairly low prices.

The U.S. Department of Commerce initiated AD and countervailing duty (CVD) investigations in July 2026, and the United States International Trade Commission (USITC) subsequently found a reasonable indication of injury to the US industry, allowing the investigations to proceed. The alleged dumping margins are substantial, ranging from 73% to over 300%. AD and CVD investigations are intended to protect US industries and workers from unfairly priced or subsidized imports as evidenced by this case regarding choline from China.

Choline is an essential nutrient used in poultry feed, swine feed, aquaculture, infant formula, human dietary supplements, functional foods and nutraceuticals.

Global Alpha participates in choline manufacturing through Balchem Corporation (BCPC US), a specialty ingredients company that operates at the intersection of nutritional science, microencapsulation technology and precise formulation.

Balchem focuses on niche markets where science-backed efficacy and stringent regulatory compliance allow for premium pricing, instead of competing as a bulk commodity supplier. The company is the global leader in choline production, dominating the market across both human and animal nutrition segments.

Rather than treating choline as a cheap bulk commodity, Balchem has spent over 50 years leveraging its proprietary manufacturing, purity testing and delivery technologies to command the leading global market share. The company’s revenue is diversified across three core business segments:

  • Human nutrition & health (63% of revenue): High-margin specialty ingredients like branded choline, mineral amino acid chelates, vitamin K2 and texturizing systems used in dietary supplements, infant formula and functional foods.
  • Animal nutrition & health (23% of revenue): Rumen-protected microencapsulated nutrients and choline delivery mechanisms that optimize health and milk production in dairy cattle and livestock.
  • Specialty products (14% of revenue): High-purity gases and packaged chemicals used primarily in medical device sterilization, agricultural fumigation and plant micronutrient delivery.

As regulation continues to reshape agricultural costs and competitiveness, locally focused producers with resilient supply chains may be best positioned to manage inflationary pressures – a thematic we continue to follow closely at Global Alpha.